ASX copper shares finally have the copper price support the bulls have promised for years.
Copper set an all-time high in London this week.
The London Metal Exchange three-month price closed at US$14,415.50 a tonne on Monday, a gain of 0.57%.
The metal has advanced roughly 17% over the past year.
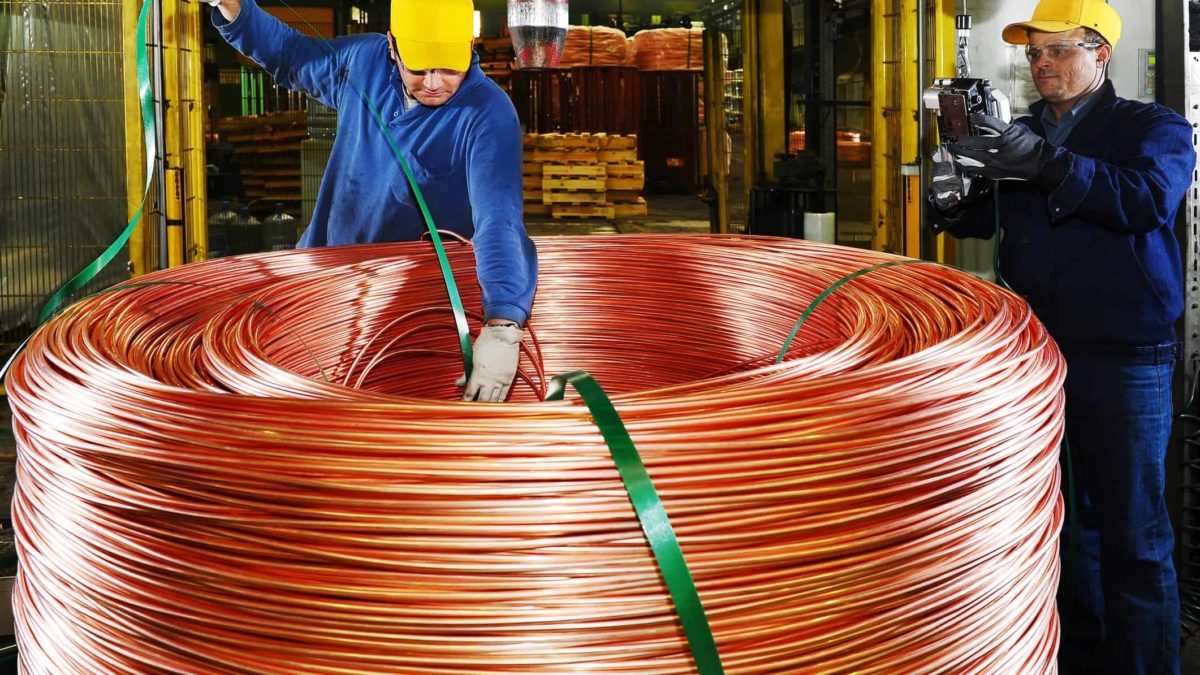
Image source: Getty Images
Why the copper price matters for ASX copper shares
Copper is unique among commodities because demand is structural in today's world.
Electricity grids, data centres, and renewable generation all consume enormous volumes of it.
Supply is the harder half, because new mines take a decade to build.
BHP has been transparent about where it sees the opportunity, describing copper as the engine driving the company's growth.
The company has a project pipeline across Chile, Australia, and Argentina that it believes can lift copper production by around 40% by FY35.
Copper climbed to record levels on Tuesday while most of the market fell.
The important point for investors is that a record price does not lift every producer equally.
Costs, grades, and operational reliability decide who converts the price into cash.
1. Sandfire Resources Ltd (ASX: SFR)
Sandfire Resources is the purest copper exposure on the ASX and the clearest winner of the three.
Shares closed at $22.50 and are up 82.93% over twelve months.
FY26 was a transformational year, capped by record sales and a much stronger balance sheet.
Revenue rose 41% to US$1,654 million and underlying EBITDA rose 64% to US$867 million.
Net profit jumped 282% to US$354 million on production of 154.2 thousand tonnes of copper equivalent.
The company moved into a net cash position and declared a 35 cent fully-franked final dividend, its first since 2022.
FY27 guidance calls for 150 to 166 thousand tonnes of copper equivalent.
Managing director Brendan Harris had this to say:
We have the right team, we have the right strategy, and we're producing the commodities the world needs to decarbonise.
2. 29Metals Ltd (ASX: 29M)
29Metals is the cautionary tale in this group.
The shares are down 4.65% over twelve months.
The half-year result showed precisely why a high copper price is not enough on its own.
Revenue rose 12% to $304.9 million, yet the company swung to a net loss of $34.8 million from a $35.3 million profit.
EBITDA collapsed from $112.6 million to $30.5 million and no interim dividend was declared.
The problems are linked to operational events.
Seismic events at Xantho Extended forced a temporary exclusion zone and gutted zinc production at Golden Grove.
Capricorn Copper remains suspended while tailings approvals work through the system.
Finally, a $150 million entitlement offer lifted liquidity to $202.1 million, which buys management time rather than solving anything.
3. BHP Group Ltd (ASX: BHP)
BHP is a diversified way to buy into the copper thematic.
FY26 was the year copper overtook iron ore inside the business.
BHP produced roughly two million tonnes of copper for a second consecutive year.
Copper contributed more than half of group underlying EBITDA for the first time, out of a group total near US$33 billion.
Net debt finished below US$9 billion and the final dividend was 99 US cents per share, the largest in four years.
The trade-off is dilution of the theme.
Iron ore still matters enormously to BHP, and it is not at a record price.
Foolish takeaway
The copper price is doing what the long-term bulls said it would.
However, the difference in fortunes between Sandfire and 29Metals this year proves not every miner is a buy.
I would rather pay up for a producer already converting a record price into cash than buy the cheapest option on the market.
ASX copper shares have rarely had a better backdrop, and the risk now sits with the companies rather than the commodity.