



The Kogan.com Ltd (ASX: KGN) share price has shot higher. It's up a hefty 81% since 23 January 2024, and it has gone up around 90% in the past year.
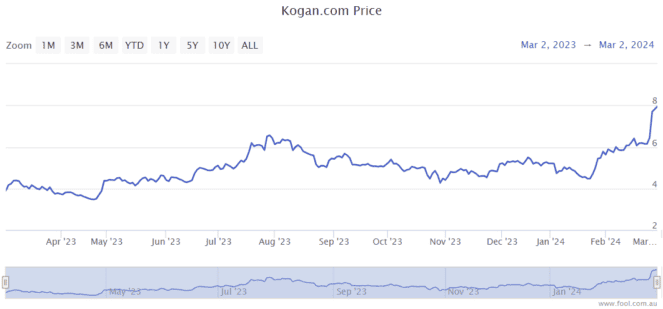
Yes, the lower Kogan share price is now in the past. But, the question is now whether it's worth investing in the online retailer for the long-term after it has risen so much.
Regardless of what we do, I think it's almost certain that the Kogan share price is going to see some more volatility in the months and years ahead.
Image source: Getty Images
What justifies the rise in Kogan shares?
The recent FY24 first-half result saw a number of positives.
Gross profit jumped 42.2% to $89.5 million, with the gross profit margin rising 13.2 percentage points to 36.1% thanks to the optimisation of inventory and focus on platform and software-based subscription revenue.
Kogan FIRST subscribers rose 15.3% year over year to 466,000 – this program delivered $22.7 million of revenue, an increase of 109.7%.
The e-commerce ASX share revealed big improvements in its other profit margins, from losses to profits. It made $19.4 million of earnings before interest, tax, depreciation and amortisation (EBITDA), $11.9 million of earnings before interest and tax (EBIT) and $8.7 million of net profit after tax (NPAT).
It also noted the new advertising platform was launched, allowing the marketplace sellers to market their listings on the platform – this delivered $1.3 million in the first half. The company expects that scaling of the platform will continue in the second half.
Strong outlook
The trading update and outlook were also very positive.
Kogan shares may have benefited when investors learned that the business generated adjusted EBITDA of $4.9 million in January 2024.
It said it's expecting continued growth of the platform-based sales contribution, an improving gross margin and operating leverage, continued improvement in product divisions' profitability, accelerated growth of the advertising platform and Mighty Mobile (New Zealand mobile), further growth of Kogan FIRST subscribers and maintenance of a "strong balance sheet".
Things are suddenly looking up for Kogan.
My view on the Kogan share price
The COVID-19 period was a feast and then famine for shareholders. It seems the ASX share has reached a much more stable footing.
If growing scale can mean rising profit margins, then Kogan's share price could keep rising over time. Its e-commerce platform has the potential to deliver good operating leverage.
The company pointed out that its EBIT margin was 4.5% in the first half of FY19, and it rose to 4.8% in the first half of FY24.
Broker UBS has estimated that FY25 could see Kogan generate earnings per share (EPS) of 23 cents, which would put the current Kogan share price at 34x FY25's estimated earnings. FY28 is a long way away, but UBS' current projection suggests the Kogan share price is at 18x FY28's forecast earnings.
I think more people are going to do more shopping online in the coming years. If Kogan can continue to offer good value and advertise well, it can become a larger business and benefit from the e-commerce tailwinds.
I'd prefer to buy it at a lower price, but I believe Kogan shares can outperform over a three-year or five-year period.








