Up 30% in 3 months, why Lovisa shares can keep sparkling: UBS

This could be a shining opportunity on the ASX, according to one expert.

Key points
  • Broker UBS just bumped up its price target to $29, implying a possible rise of around 20%
  • Lovisa is rapidly growing its store network, which can help operating leverage
  • Its total revenue to date in FY23 has grown by 60%

The Lovisa Holdings Ltd (ASX: LOV) share price has risen by 30% in three months and 80% in five months. It has been on a very strong run.

The jewellery retailer has been reporting a lot of growth in both FY22 and the start of FY23.
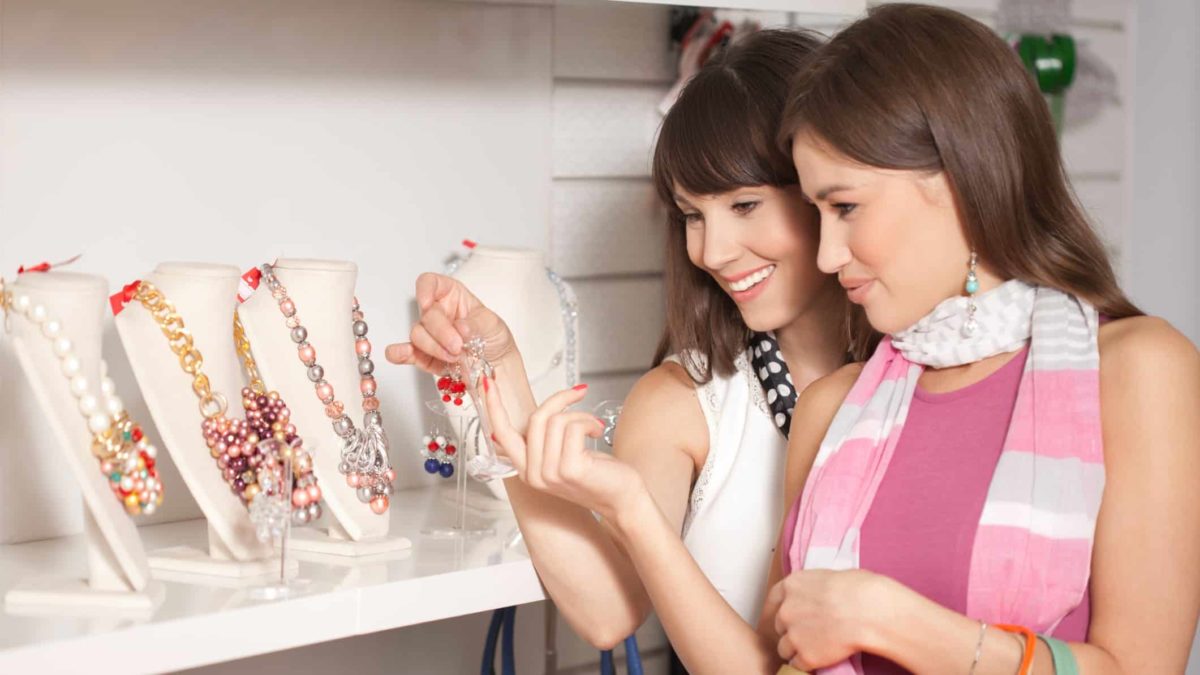
Two women shoppers smile as they look at a pair of earrings in a costume jewellery store with a selection of large, colourful necklaces made of beads lined up on a display shelf next to them.

Image source: Getty Images

Impressive growth

The ASX retail share saw its total revenue rise by 59.3% to $458.7 million in the 2022 financial year. It saw "strong momentum through the financial year". Comparable store sales went up 19.9% and it opened 85 net new stores during the period – finishing with 629 at the year-end.

FY22 total gross profit increased by 63.8% to $361.8 million, earnings before interest and tax (EBIT) went up 86.6% to $79.7 million, and net profit after tax (NPAT) rose 116.3% to $59.9 million.

In the first 19 weeks of FY23, global comparable store sales increased 16.1% compared to FY22 for the year to date, with total sales for that period up 60%.

It has opened 47 net new stores in the year to date. It recently opened in the new markets of Canada, Poland, Namibia, and Hong Kong. Lovisa is also planning to open its first stores in Italy, Mexico, and Hungary in the "coming weeks".

Broker views on the Lovisa share price

As reported by the Australian Financial Review, the broker UBS increased its price target from $20 to $29. That's an increase of 45%, so the broker is much more optimistic about the outlook.

It thinks that the store rollout plan by Lovisa is "compelling" when compared to global peers. Despite the bigger number of stores, UBS notes that the growth is accelerating.

The growth of the size of Lovisa's store network led to UBS bumping up its earnings per share (EPS) forecasts by 24% for FY23 and 35% for FY24.

UBS thinks that Lovisa can grow its revenue to $958 million in FY25, up from $459 million in FY22. Part of the confidence for this projection is due to new CEO Victor Herrero, who has prior experience in growing a business.

UBS suggested that the business has "significant store growth potential across both existing and new markets", while the ASX share's younger core customer base and lower pricing point means it can handle this environment well.

The broker also suggested that becoming larger with a bigger store count can help the business grow its profit margins, which can offset the start-up costs in new markets.

Lovisa share price valuation

The Lovisa share price closed on Monday at $24.45. If Lovisa shares reach $29, that would be a potential rise of almost 20%.

At the current level, the retailer is valued at 32x FY23's estimated earnings and 24x FY24's estimated earnings.
Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended Lovisa Holdings Ltd. The Motley Fool Australia has recommended Lovisa Holdings Ltd. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Broker Notes

Happy miner with his arms folded.
Broker Notes

Buy, hold, sell: Paladin Energy, Fortescue, Rio Tinto shares

Let's take a look at some new ratings from Morgans.

Read more »

a man in a business suite throws his arms open wide above his head and raises his face with his mouth open in celebration in front of a background of an illuminated board tracking stock market movements.
Broker Notes

9 ASX 200 shares experts are backing for growth amid market weakness

Brokers retained a positive view on BHP, CSL, Telstra, Xero, and other shares this week. 

Read more »

Medical workers examine an x-ray or scan in a hospital laboratory.
Broker Notes

This ASX biotech could rise 40% or 750%, depending on who you ask

A poor quarter has reduced expectations, but there's still plenty of upside.

Read more »

Man using his device in an airport.
Broker Notes

This high-quality ASX 200 share could rise 60%

A leading broker expects a good yield and major upside from this stock.

Read more »

A baby's eyes open wide in surprise as it sucks on a milk bottle.
Broker Notes

Trading near 12-month lows, this ASX retailer could be set for a 54% gain

This baby goods retailer still has ample room to grow.

Read more »

three young children weariing business suits, helmets and old fashioned aviator goggles wear aeroplane wings on their backs and jump with one arm outstretched into the air in an arid, sandy landscape.
Broker Notes

5 ASX 200 stocks analysts have upgraded this week

Brokers have increased their ratings on PLS Group, Mineral Resources, Ampol, and other stocks. 

Read more »

Children skipping and jumping up a hill.
Broker Notes

3 ASX small-cap shares with 48% to 128% upside ahead: Morgans

The ASX Small Ords Index has collapsed 18% in 2026 and this broker sees buying opportunities.

Read more »

A male investor wearing a blue shirt looks off to the side with a miffed look on his face as the share price declines.
Broker Notes

6 ASX shares hit by broker downgrades this week

Brokers reduced their ratings on South32, Boss Energy, Sonic Healthcare, and other stocks.

Read more »