This defence stock could deliver returns close to 20% Macquarie says

This shipbuilder is well-placed for growth, given the increase in defence spending.

Key points
  • Strong defence spending will be a boon for Austal going forward.
  • The company is looking to build on last year's near-record earnings.
  • Macquarie analysts say the shares should outperform.

With defence spending increasing in Australia and global tensions high, it's fair to say that the outlook for local shipbuilder Austal Ltd (ASX: ASB) is looking ship shape.

Now that we have that terrible pun out of the way, let's move on to the serious business of having a look at how the company is travelling, and indeed, things are looking good.

The company held its annual general meeting (AGM) this week, and reiterated the theme that defence spending as a proportion of gross domestic product is trending upwards.
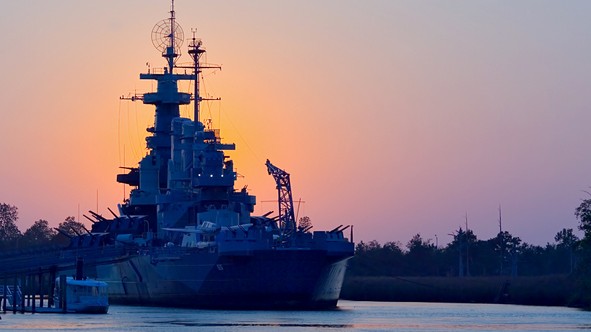
Navy ship sailing at dusk.

Image source: Getty Images

Earnings set to grow

Managing director Paddy Gregg, in his presentation to the AGM, said the company was building from a solid base with near-record underlying earnings of $113.4 million "ahead of expectations" in FY25 and up strongly from $56.4 million the previous year.

And promisingly the company could expect "continued growth … for years based on order book and government-announced contracts''.

There would also be additional opportunities for growth via the AUKUS defence agreement between Australia, the US and the UK under which Australia will procure its next generation of submarines.

Mr Gregg said the company was expecting earnings to continue to grow this year to $135 million, with key drivers the company's record order book, an increased volume of work in Asia and increased orders expected under Australia's Strategic Shipbuilding Agreement.

Stocks worth a look

The team at Macquarie have run the ruler over the Austal balance sheet, and like what they see.

Austal's diversified order book "positions it strongly for medium-term earnings growth", the Macquarie analysts said in a research note sent to clients this week.

As they said:

Austal is one of few ASX firms that provides exposure to rising global defence spending including material exposure to the US (about 75% of FY25 revenue).

The Macquarie analysts said the company was tracking well towards its FY27 revenue target of $500 million, "with addressable market growing in both US and Australia and investment in (its) San Diego floating dock ongoing''.

They noted that once the San Diego dock was operational in early FY26, it would enable Austal to work on non-Austal ships.

Macquarie has upgraded Austal shares from a neutral rating to outperform and has a price target of $8.10 on the shares compared with the $6.81 closing price on Wednesday.

If that level is reached, shareholders would be sitting on gains of 18.9% over a 12-month period.

Austal does not pay dividends. The company was valued at $2.87 billion at the close of trade on Wednesday.
Motley Fool contributor Cameron England has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Broker Notes

Shot of a young businesswoman looking stressed out while working in an office.
Broker Notes

6 ASX stocks receiving analyst downgrades this week

Brokers reduced their ratings on NextDC, Ampol, Regis Resources, and other stocks this week. 

Read more »

Facebook thumbs up symbol surrounded by boxes with the word 'Like'.
Broker Notes

6 ASX stocks upgraded by leading brokers this week

Brokers have raised their ratings on Pro Medicus, South32, New Hope, and others. 

Read more »

Buy now written on a red key with a shopping trolley on an Apple keyboard.
Broker Notes

6 ASX shares experts are backing amid the market downturn

Brokers maintained a positive view on Qantas, NAB, Maas Group, BHP, and other shares.

Read more »

Two work colleagues looking at a laptop and discussing something.
Broker Notes

Should you buy Hub24, Northern Star, and Transurban shares?

Morgans has given its verdict on these shares. Is it time to buy? Let's find out.

Read more »

Man and woman holding a tablet and clipboard while looking at the backside of server racks in a data centre.
Broker Notes

Buy, hold, sell: Sigma, Cliunvel, and NextDC shares

Let's see how analysts rate these shares this week.

Read more »

AI microprocessor on motherboard computer circuit.
Broker Notes

Xero or hero? UBS predicts the latter with huge upside for the accounting stock

AI is not all doom and gloom for this accounting software provider.

Read more »

Diagram of black male figure with question marks on top and arrows on wooden blocks on each side.
Broker Notes

Buy, hold, sell: JB Hi-Fi, Xero, Northern Star Resources shares

Experts reveal their ratings on 3 ASX shares in the retail, gold mining, and tech segments.

Read more »

An ASX 200 market analyst holds his hand to his chin and looks closely at his computer screens watching share price movements
Broker Notes

Buy, hold, sell: Ramelius Resources, Harvey Norman, Santos shares

Let's check out some new ratings on ASX shares today.

Read more »