
Viva Energy vs Ampol shares: Which energy share has a bigger upside?

The broker updated investors with its latest outlook.

Key points
  • ASX energy stocks Ampol and Viva Energy are popular for income-focused investors seeking oil and gas sector exposure, with Ampol expanding its network via a $1.1 billion acquisition of EG Australia.
  • Macquarie maintains a neutral outlook on both stocks, projecting a modest 2.2% upside for Ampol with a target price of $31, and a potential 26.1% increase for Viva Energy with a $2 target price despite uncertainties in its OTR rollout.
  • Both companies are leveraging strong refining margins, but Ampol focuses on disciplined M&A, while Viva Energy addresses leadership transition and strategic expansion, reflecting distinct growth dynamics.

ASX energy shares, particularly fuel distribution stocks like Apmol Ltd (ASX: ALD) and Viva Energy Group Ltd (ASX: VEA), are a popular option among income-focused investors who want exposure to the oil and gas industry.

Petroleum refiner and distributor Ampol is currently in an expansion phase and has recently agreed to acquire EG Australia for $1.1 billion. EG owns and operates around 500 service stations in Australia, and its network is Ampol's largest dealer network.

The acquisition is expected to add around $53 million of EBIT to Ampol's earnings in the 2026 calendar year. The move is also expected to add another $172 million EBIT in the 2027 calendar year.

At the time of writing on Friday afternoon, Ampol shares are 1.71% higher and changing hands at $30.33 per share. For the year, the shares are 0.26% higher.

Meanwhile, transport fuel supplier Viva Energy continues to focus on cost-reduction initiatives and has recently announced a change of leadership in its Convenience and Mobility business. 

Late last month, the business announced that its CEO, Jevan Bouzo, has resigned and will leave at the end of the year. Group COO Jennifer Gray will be interim CEO while the company looks for a permanent replacement.

At the time of writing, Viva Energy shares are 0.28% higher and trading for $1.785 a piece.

The two businesses are clearly in a development phase. So, which is the best option for investors?
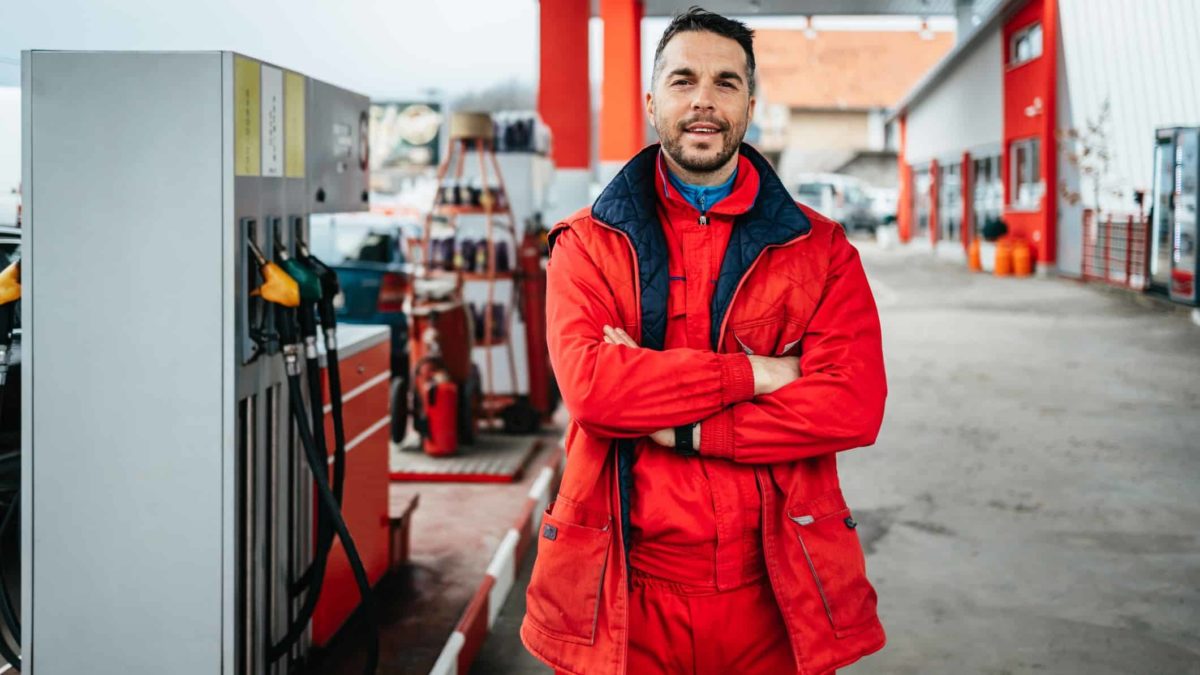
A service station attendant crosses his arms and smiles towards the camera with a backdrop of petrol bowsers and a drive-through facility.

Image source: Getty Images

Macquarie's take on Ampol and Viva Energy shares

In a recent note to investors, the broker confirmed its neutral outlook on Ampol shares and raised its 12-month target price to $31. At the time of writing, that represents a potential upside of 2.2%.

The broker said it sees disciplined merger and acquisition and solid execution from Ampol.

"Earnings: We raise 2025e EPS by 2.5% which reflects stronger refining margins (driven by SWAM) partly offset by lower F&I (costs)," Macquarie said in its note.

"Valuation: Our P/E based TP remains based on 16x, and TP is +2.5% to $31.00/sh based on the increased earnings. We believe ALD is executing well, however are waiting for a better re-entry point in the stock."

The broker also confirmed its neutral outlook on Viva Energy shares and lowered its target price to $2 per share. But that represents a potential upside of 26.1% for investors over the next 12 months.

It explained that it sees an uncertain OTR rollout, which has driven a lower multiple for now. Viva Energy plans to expand its OTR convenience store brand following the acquisition of the model in 2024.

"Earnings: We raise 2025e EPS by ~8% on stronger refining margins, and cut 2026-28e EPS by ~4% on slightly lower refinery utilisation (based on disappointments in recent years)," the broker said.

"Valuation: We lower our 12-mth P/E multiple to 12x (was 14x) given the now increased uncertainty associated with the OTR rollout & profit uplift (and TP -11% to $2.00/share)."

Macquarie said it expects most of the 2Q strength in the fuel market to continue into 3Q.

"Notably, Melbourne/Sydney/Brisbane have held up well in petrol, yet Adelaide softened quite a bit… Petrol volumes sold at retail outlets continue to decline meaningfully YoY (4% YTD YoY Jan-Jul)."

Motley Fool contributor Samantha Menzies has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Energy Shares

Oil worker using a smartphone in front of an oil rig.
Energy Shares

How many Woodside shares do I need to buy for $1,000 per month of passive income?

Find out what you could earn off your oil and gas investment.

Read more »

Engineer in the oilfield wearing red helmet and work clothes, with pumpjack and wellhead in the background.
Energy Shares

Woodside Energy vs Ampol: Which ASX oil stock looks better this week?

Woodside Energy and Ampol both offer franked income, but one oil stock looks better value to me right now.

Read more »

An oil worker in front of a pumpjack using a tablet.
Broker Notes

2 ASX energy companies Macquarie says will outperform

There's still some value in the volatile energy sector, the broker says.

Read more »

Engineer at an underground mine and talking to a miner.
Broker Notes

Up 42% and paying a 7% dividend yield, should I buy New Hope shares today?

A leading expert delivers his outlook for New Hope’s outperforming shares.

Read more »

A man scratches his head in confusion.
Energy Shares

This ASX energy stock just crashed 12%. Here's what's gone wrong

Investors are heading for the exits.

Read more »

A woman wearing a black and white striped t-shirt looks to the sky with her hand to her chin, contemplating buying ASX shares.
Energy Shares

Boss Energy vs Paladin Energy: Which ASX uranium stock wins?

Boss Energy and Paladin Energy are ASX uranium leaders. Here’s which I’d buy based on value, growth, and latest performance.

Read more »

A mining worker clenches his fists celebrating success at sunset in the mine.
Broker Notes

Macquarie says this ASX uranium producer has more than 15% upside

A new mine design has impressed the broker.

Read more »

A service station attendant crosses his arms and smiles towards the camera with a backdrop of petrol bowsers and a drive-through facility.
Energy Shares

Woodside vs Ampol: Which ASX energy stock should you buy?

Woodside and Ampol both offer franked dividends and momentum—so which ASX energy stock wins out on value and yield?

Read more »






