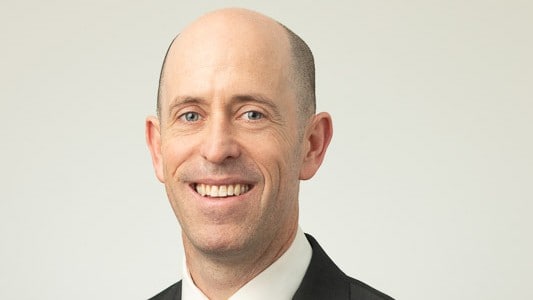
Image source: Glenmore Asset Management
Ask A Fund Manager
The Motley Fool chats with fund managers so that you can get an insight into how the professionals think. In this edition, Glenmore Asset Management portfolio manager Robert Gregory describes the philosophy behind his fund's industry-topping outperformance.
Investment style
The Motley Fool: How would you describe your fund to a potential client?
Robert Gregory: Glenmore Fund, it's market cap agnostic, so it can invest in any market cap — small, mid-cap, large. And it's only on Australian equities. And within the ASX, it's got a focus on small to mid-cap space… probably $200 [million] up to $2, $3 billion. That's where most of the outperformance has been identified.
I'm really a buy-and-hold type investor looking to buy stocks that I can see [are] undervalued, and then hopefully hold them for quite a few years, if possible.
In terms of the reasons why I see a stock as being undervalued, that can often just be the market underestimating that company's earnings potential. Or it might be the market's [underreaction] to an improving earnings outlook, or an acquisition that's been particularly positive. Or it might just be that stock is going through a temporary difficult period for its earnings, but I think it's temporary and not long-term.
It's still neutral — so it's not really growth nor value. It probably has a slight bias towards what I'd call quality businesses, where I'm not really interested in early-stage development-type businesses. I'm really much focused on established businesses that have been profitable for a long period of time. Hence, you can have more confidence that they can sustain themselves through challenging economic periods.
The vast proportion of the fund would pay dividends, for example. So they're quite established businesses and companies that I've got to know over a long period of time and got to know the management over a long period of time as well. A lot of the companies know that they're in my fund, I've dealt with the CEOs and CFOs for many years now.
MF: Mercer ranked Glenmore as the best-performing fund in Australia for the year ending 31 March, with a 50.8% return. Congratulations, and can you tell us if there were any star performers that carried you to that amazing result?
RG: It was probably four to five stocks that created a fair amount of the outperformance, but it was reasonably well spread even below that top five.
But some of the top performers were Uniti Group Ltd (ASX: UWL), MA Financial Group Ltd (ASX: MAF), Bowen Coking Coal Ltd (ASX: BCB), and also Whitehaven Coal Ltd (ASX: WHC).
MA Financial and Uniti were really situations where they delivered very strong earnings and saw their stock prices and earnings multiples rebate accordingly.
Whitehaven… was coming from a very depressed period of coal prices and its valuation was very depressed. And then, as seen, the thermal coal price rallied quite significantly and, as such, it's earning some cash flow generation [and has] recovered very strongly.
At the small cap end, Bowen Coking Coal, which is a stock that I identified probably 18 months ago back when it had a very small market cap, was run by a management team that I had a lot of confidence in.
I saw their strategy of acquiring at very cheap, at very low cost and satellite deposits to get up and running and get into production, and build cash flow. And at that point in time, particularly when I first started buying BCB, the stock price was sort of 6, 7, 8 cents. It just looked [like] a very asymmetric situation where not much was in the stock price at all at the market cap, but I felt if they could opportunistically acquire some coal assets, then it would be worth significantly more than that market cap.
So it's come from a range. Certainly, coal was definitely helpful, but there's also been a number of other stocks that have performed very strongly as well.