DroneShield shares just hit a new low. Is the only way up from here?

Risk-takers may see opportunity here. Others should just watch.

DroneShield Ltd (ASX: DRO) shares are in freefall, and investors are starting to ask an uncomfortable question.

The counter-drone technology company closed at $1.60 on Monday, a fresh 52-week low, leaving the share price a staggering 76% below its previous high of $6.70, reached at the end of October last year.

When a stock falls that hard, the temptation to call a bottom gets stronger. But is the risk-reward actually tempting enough to buy? Or is this a falling knife dressed up as a bargain?
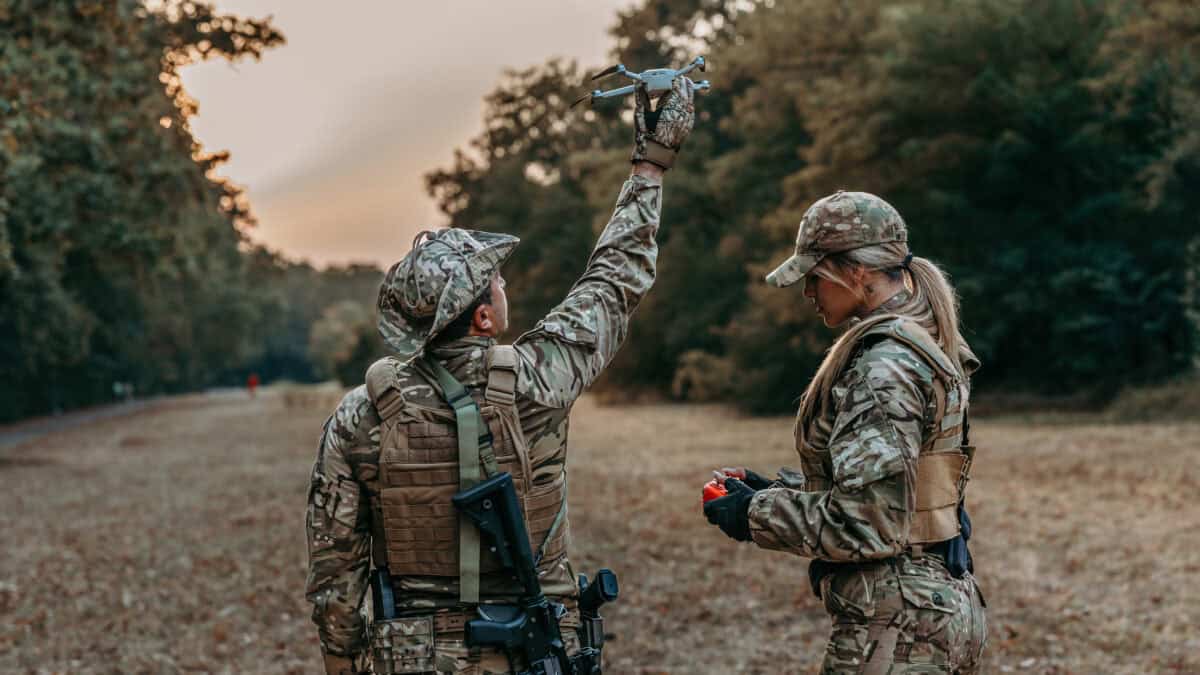
Army man holding a drone while the army woman holds the remote control.

Image source: Getty Images

The demand story hasn't gone anywhere

The numbers tell a grim story. DroneShield shares are down 20% over the past month and 49% over the past year. For a stock that was once one of the ASX's hottest momentum plays, this is a stunning reversal of fortune.

Here's the twist, though. While the share price has collapsed, the underlying business case hasn't. Drones are not going away. If anything, they're becoming more central to modern warfare, border security and the protection of critical infrastructure. That means governments and defence customers still need systems that can detect, track and stop them.

DroneShield is actually converting that demand into hard revenue. Its latest update showed FY26 committed revenue had reached $251 million, with a further $46 million already committed for FY27 and beyond. First-half revenue surged 74% to $125.8 million, while recurring revenue rocketed 229% to $11.5 million — a sign the business is shifting from one-off sales toward something stickier.

The company also landed its first order for its new RfRecon product from an existing Western European military customer. It's not financially material yet, but it's early validation for another product in an expanding range.

The catch: this is still a loss-making bet

None of that changes the fact that DroneShield is bleeding cash. First-half underlying EBITDA was $12.4 million in the red, and the statutory loss came in at $32.2 million.

DroneShield shares remain one of the highest-risk stocks on the ASX. Defence contracts don't arrive on a neat schedule, so revenue can be lumpy and unpredictable.

The company is scaling fast, but investors still need proof that bigger revenue eventually turns into sustainable profit, not just bigger losses. And as governments pour more money into counter-drone systems, larger, better-funded defence contractors could pile into the same opportunity, squeezing DroneShield's edge.

What are the brokers saying?

TradingView data shows just four analysts cover the stock — split evenly, with two buys and two sells.

The average 12-month price target for DroneShield shares sits at $1.99, roughly 24% above the current share price. Bell Potter is the most bullish at $2.40, with Canaccord Genuity close behind at $2.60.

Foolish takeaway

DroneShield isn't a stock for the faint-hearted. The growth numbers are genuinely exciting, but the losses, volatility and competitive threats are just as real.

For risk-tolerant investors who believe in the counter-drone thematic, this pullback might be the entry point they've been waiting for. For everyone else, this is one to watch from the sidelines.
Motley Fool contributor Marc Van Dinther has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended DroneShield. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Technology Shares

A boy bounds after a big colourful bouncing ball in a grassy field.
Technology Shares

Life360 shares rebound 9% on Wednesday. What on earth is going on with the ASX tech stock this week?

The shares are storming higher again today.

Read more »

Happy woman working on a laptop.
Technology Shares

Why these are 3 of my favourite ASX tech shares to buy

I've been looking at three companies with strong positions in their markets and opportunities to become much bigger.

Read more »

A man with his back to the camera holds his hands to his head as he looks to a jagged red line trending sharply downward.
Technology Shares

Life360 shares have plunged on results. Why I think they're still a compelling buy

Is it time to buy the dip?

Read more »

Two colleagues looking at a graph and comparing share prices.
Technology Shares

Why I'd buy and hold WiseTech shares for 10 years or more

The way this business makes money is changing, and I think that could open the door to years of growth.

Read more »

A cute little kid in a suit pulls a shocked face as he talks on his smartphone.
Technology Shares

Codan has dropped a quarter of a billion dollars on a new acquisition

Codan's looking to grow its smaller, third division.

Read more »

IT specialist using laptop in data centre full of server racks.
Technology Shares

The 'share raid' that rocketed the NextDC share price

Is a takeover bid in the wings?

Read more »

Man looking down and trying to work his laptop.
Technology Shares

Why I'd invest $10,000 in HUB24 shares this month

The shares aren't cheap, but I think the company's growth opportunities make it worth considering for a long-term investment.

Read more »

Man looking at digital holograms of graphs, charts, and data.
Technology Shares

2 out of these 3 ASX tech stocks could double your money

Brokers are tipping strong returns from these companies.

Read more »