Is Rio Tinto still one of the best shares to buy heading into 2026?

Rio Tinto shares are up strongly in 2025. Is the mining giant still worth buying heading into 2026?

Key points
  • Rio Tinto shares have risen by 24% in 2025 due to strong iron ore and copper market conditions, supported by increasing demand for electrification.
  • The company’s diversification into copper, aluminium, and lithium reduces dependency on iron ore, enhancing resilience against potential market fluctuations.
  • Strong dividends and a solid balance sheet continue to make Rio Tinto an attractive option for income-focused investors, despite potential risks from economic conditions and commodity price changes.

Shares in Rio Tinto Ltd (ASX: RIO) have been back in form recently.

The mining giant's share price is up around 10% over the past month and has climbed roughly 24% over 2025. That puts Rio Tinto among the stronger performers in the ASX large-cap resources sector this year.

With the share price pushing higher again, investors are now asking whether Rio Tinto still stacks up at today's prices as we look ahead to 2026.

Let's take a dive.
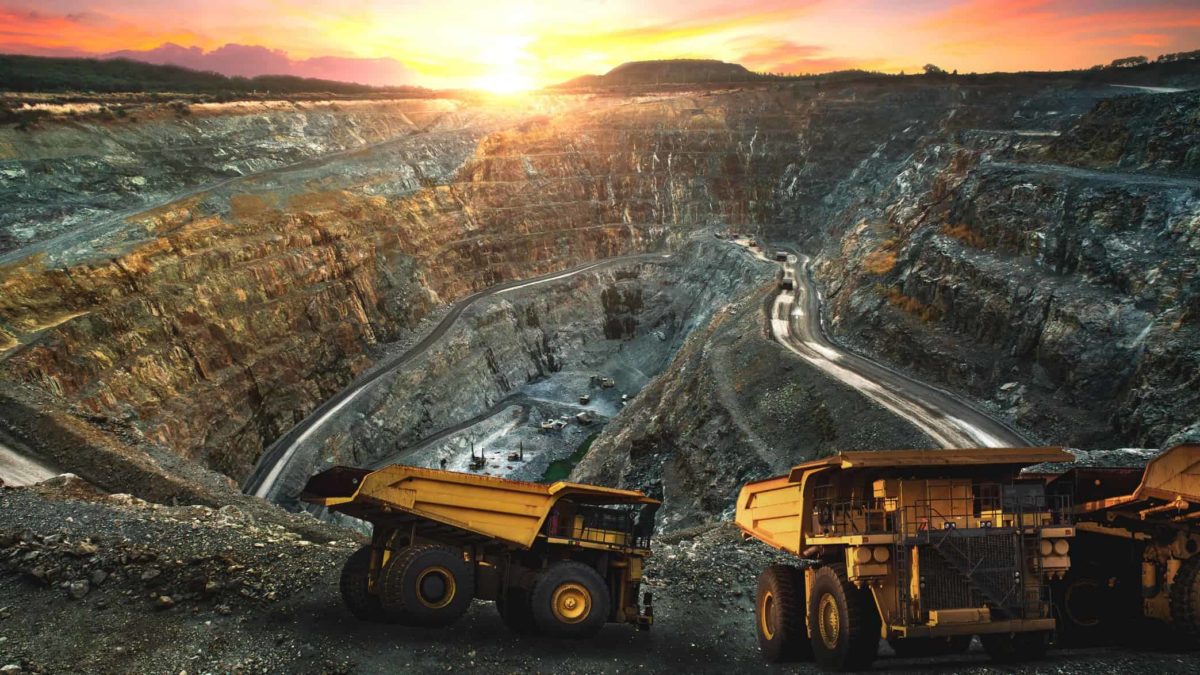
View of a mine site.

Image source: Getty Images

A strong year for Rio Tinto shares

Rio Tinto has benefited from better conditions across commodity markets in the second half of 2025.

Iron ore prices have held up better than expected, while copper prices have stayed high due to tight supply. Strong demand for copper linked to electrification has also helped support earnings expectations across the business.

Together, these factors have pushed Rio Tinto shares back toward the top of their recent trading range. Compared with other large miners, Rio has delivered steady gains rather than sharp share price swings.

What are brokers saying?

Broker views on Rio Tinto remain mixed but generally supportive.

Some analysts remain cautious on iron ore prices heading into 2026. Westpac, for example, has warned that iron ore prices could ease from current levels as new supply comes online and Chinese steel demand stays under pressure.

However, most brokers also stress that Rio Tinto is not just an iron ore company.

Copper, aluminium, and lithium are becoming more important to the business and now make up a larger share of earnings. Demand for these commodities is expected to grow over time, which helps reduce reliance on iron ore prices.

Dividends remain a big attraction

One area where Rio Tinto continues to stand out is dividends.

In 2025, the company paid two large dividends to shareholders. This included an interim dividend of $2.22 per share and a final dividend of $3.71 per share.

That takes total dividends paid in 2025 to around $5.93 per share, supported by strong cash flow and a solid balance sheet.

Of course, future dividends will always depend on commodity prices, which can move up and down. However, Rio Tinto's size, low-cost operations, and strong cash generation give it a good base to keep paying income over time.

More than iron ore

Rio Tinto is also working to grow parts of the business outside iron ore.

The company is investing more in copper, which it believes will be an important metal over the next decade. Projects in Australia, Mongolia, and the Americas are aimed at increasing copper production over time.

Rio Tinto is also building its lithium business, giving it exposure to battery materials used in electric vehicles.

Together, these moves help spread risk and reduce reliance on any single commodity.

However, that does not remove risk completely.

Like all miners, Rio Tinto is still affected by global economic conditions. A sharper slowdown in China, weaker commodity prices, or higher costs could all pressure earnings.

After a strong run, the share price could also pull back if investor sentiment changes.

Foolish Takeaway

Rio Tinto delivered a strong 2025, with the share price up 24% and momentum building late in the year.

While iron ore risks remain, diversification, a strong balance sheet and reliable dividends support the outlook for 2026.

The shares may not be cheap, but Rio Tinto remains a high-quality miner with income appeal and long-term exposure to key commodities.

It is a stock I am happy to keep on my watchlist heading into the new year.
Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Resources Shares

Businessman working and using Digital Tablet new business project finance investment at coffee cafe.
Resources Shares

Is the Rio Tinto share price good value after a 23% decline?

I crunch the numbers to see whether this mining giant offers good value around $150.

Read more »

Group of miners working at a coal mine with one smiling and holding up a piece of coal.
Resources Shares

Whitehaven Coal posts record Q1 production and keeps FY27 guidance

Whitehaven Coal posted record first-quarter production and reaffirmed guidance, with costs at the low end and acquisition payments nearly complete.

Read more »

Miner and company person analysing results of a mining company.
Resources Shares

Mineral Resources delivers record Q1 iron ore and lithium sales

Mineral Resources delivered record Mining Services volumes and lithium sales for Q1 FY27, with strong operational and financial updates.

Read more »

Two workers on a tablet at a mine site, with mining machinery behind them.
Resources Shares

Newmont Corporation reports robust third-quarter result and higher profit

Newmont posted higher quarterly profit and cash flow, lifted dividends, and flagged solid liquidity and new growth projects.

Read more »

a chalk drawing of a car is connected to a real green battery, signifying clean energy
Resources Shares

Lithium price set to soar 63% in FY27. Here's why and the ASX shares to buy

We reveal official commodity price forecasts and which ASX lithium shares experts rate a buy.

Read more »

A sad looking engineer or miner wearing a high visibility jacket and a hard hat stands alone with his head bowed and hand to his forehead as he speaks on a mobile.
Resources Shares

Why have Rio Tinto shares lost 23% since June?

... and what to expect out of the shares next.

Read more »

Young successful engineer, with blueprints, notepad, and digital tablet, observing the project implementation on construction site and in mine.
Resources Shares

Vault Minerals posts Q1 gold output and cash flow in September 2026 quarter

Vault Minerals delivered strong gold production, cash flow and project progress in the September 2026 quarter.

Read more »

Two people wearing hard hats talking with each other at a mine site, with two workers in the background.
Resources Shares

Nickel Industries posts record ore sales, solid EBITDA for Q3 2026

Nickel Industries delivered record Hengjaya Mine ore sales and steady EBITDA growth in the September quarter, with expansion projects progressing.

Read more »