Up 25% in 2025: Is Whitehaven Coal still a buy?

After a strong 25% run this year, investors are asking whether Whitehaven Coal still has more upside left.

Key points
  • Whitehaven Coal's share price has risen 25% in 2025, driven by solid execution, stable production, and favourable coal prices.
  • Despite some volatility, current coal prices remain supportive, helping to maintain Whitehaven's financial health and operational momentum.
  • While not a deep-value play, Whitehaven still offers benefits through disciplined cost management and potential returns, appealing to those comfortable with commodity market exposure.

The Whitehaven Coal Ltd (ASX: WHC) share price has had a strong year, climbing roughly 25% year to date and recently trading around $7.75. For a stock many investors had written off during the coal downturn, that's been an impressive rebound.

The obvious question now is whether Whitehaven still has more to offer, or if most of the upside has already been captured.
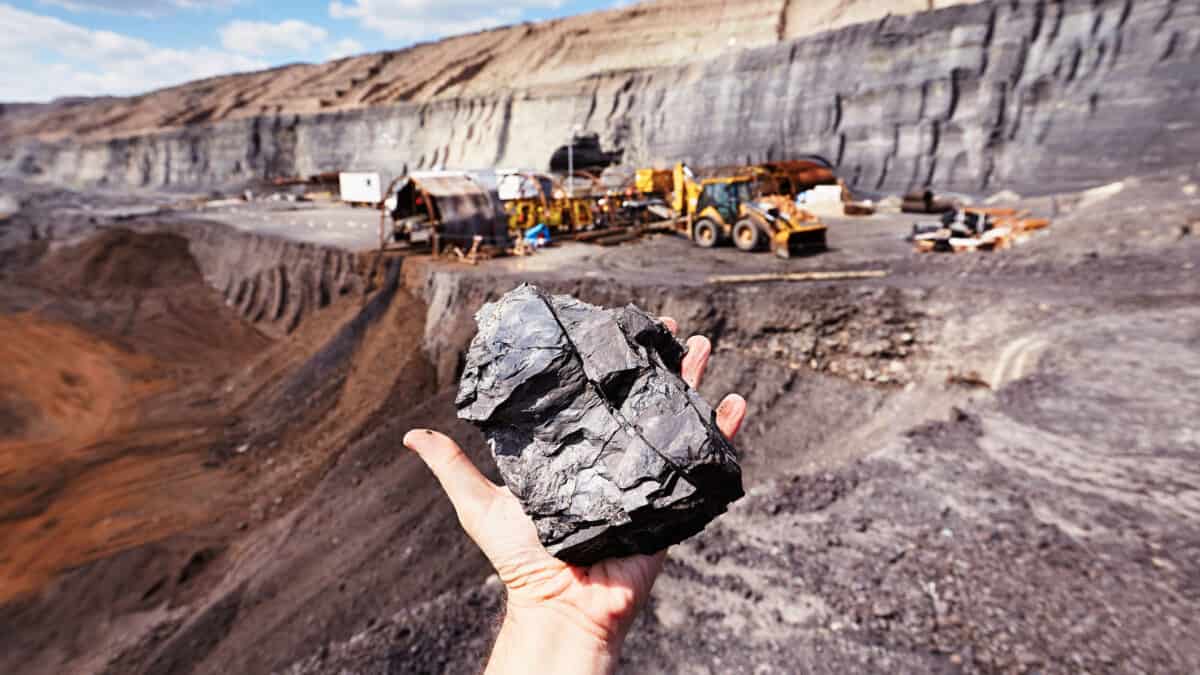
Hand holding out coal in front of a coal mine.

Image source: Getty Images

What's driving the strength?

A big part of Whitehaven's recent run has come down to execution. The company's September quarter update showed production and costs broadly tracking within guidance, while realised coal prices remained well above long-term averages.

Whitehaven reported managed run-of-mine production of 9 million tonnes for the quarter, with managed sales of 7.5 million tonnes. Unit costs were in the top half of FY26 guidance, but management reiterated expectations for costs to improve over the remainder of the year as volumes lift and cost savings flow through.

The company is also making progress on its cost-out program, targeting $60 million to $80 million in annualised savings by June 2026.

Coal prices still doing the heavy lifting

Thermal and metallurgical coal prices have come off their peaks, but they remain supportive. According to Trading Economics, Newcastle thermal coal prices are still sitting comfortably above pre-2021 levels, helping underpin margins for low-cost producers like Whitehaven.

That pricing environment has allowed Whitehaven to strengthen its balance sheet. Net debt sat around $800 million at the end of September, a manageable level given the current cash generation from the company.

What are brokers saying?

Broker views are mixed, which is fairly typical for coal stocks at this point in the cycle.

Jefferies recently lifted its price target to $8, while Bell Potter sits around $7. Macquarie trimmed its target to about $7 but still acknowledges Whitehaven's solid operational performance. Morgans and Ord Minnett have also made modest adjustments to their targets, reflecting more normalised coal prices rather than company-specific issues.

Is it still a buy?

Whitehaven is never going to be a set-and-forget investment. Coal prices are volatile, sentiment can turn quickly, and long-term demand remains uncertain.

That being said, the company is in a much stronger position than it was a year ago. Production is stabilising, costs are coming down, and the balance sheet looks far healthier. Ongoing buybacks and the potential for shareholder returns also support the case.

My take

After a 25% rally, Whitehaven is no longer a deep-value turnaround play. However, for investors comfortable with commodity exposure, it still offers leverage to coal prices, enhances operational momentum, and maintains a disciplined approach to costs.

At these levels, it's probably no longer cheap, but it's not obviously expensive either. But as long as coal prices remain supportive and execution stays on track, Whitehaven can continue to earn its place on my watchlist.
Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended Macquarie Group. The Motley Fool Australia has positions in and has recommended Macquarie Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Energy Shares

A woman holds her finger to the side of her lips in contemplation as she looks upwards to an array of graphic images of light bulbs above her head, one of which is on and glowing.
Energy Shares

Is the Woodside share price a buy following its dividend policy change?

Is the energy giant trading at attractive value?

Read more »

Oil worker using a smartphone in front of an oil rig.
Energy Shares

Woodside shares slump 5% on Thursday: Buy, sell, or hold?

Find out what happened today, and what the experts tip next.

Read more »

A woman looks sideways at a graphic near her head reading CO2 with a downward arrow.
Energy Shares

Uranium price tipped to rise 38%. Here's why and which ASX shares brokers rate a buy

Here are the official forecasts for yellowcake and which uranium shares the experts rate a buy.

Read more »

A service station attendant crosses his arms and smiles towards the camera with a backdrop of petrol bowsers and a drive-through facility.
Energy Shares

Are Santos shares still a buy after latest oil price crash?

Here's what the experts think.

Read more »

Woman calculating dividends on calculator and working on a laptop.
Energy Shares

If I invest $5,000 in Santos shares today, what could they be worth by late October 2027?

Santos shares have boomed 45% higher over the past 12 months.

Read more »

Engineer in the oilfield wearing red helmet and work clothes, with pumpjack and wellhead in the background.
Energy Shares

Would I buy Woodside or Santos shares if oil prices remain high?

One has major new developments on the way, while the other is already seeing production growth.

Read more »

An oil worker holds his hands in the air in celebration in silhouette against a seitting sun with oil drilling equipment in the background.
Energy Shares

Can Woodside shares rally to fresh 52-week high?

Are the oil and gas major's shares a buy, sell, or hold now?

Read more »

Smiling oil worker in front of a pumpjack.
Energy Shares

Woodside Energy vs Beach Energy: Which ASX energy share is better for young investors right now?

Woodside Energy vs Beach Energy: which ASX energy stock looks best a 20 year old investor?

Read more »