
Here's the outlook on ResMed shares in 2025

Can investors breath easy?

If you've been paying attention to ResMed Inc (ASX: RMD) shares lately, you would know they've been on a very strong roll.

The ASX healthcare giant has enjoyed strong momentum throughout 2024, with its share price up 45% year to date.

But what does 2025 have in store for ResMed shares? Let's dive into what the experts think.
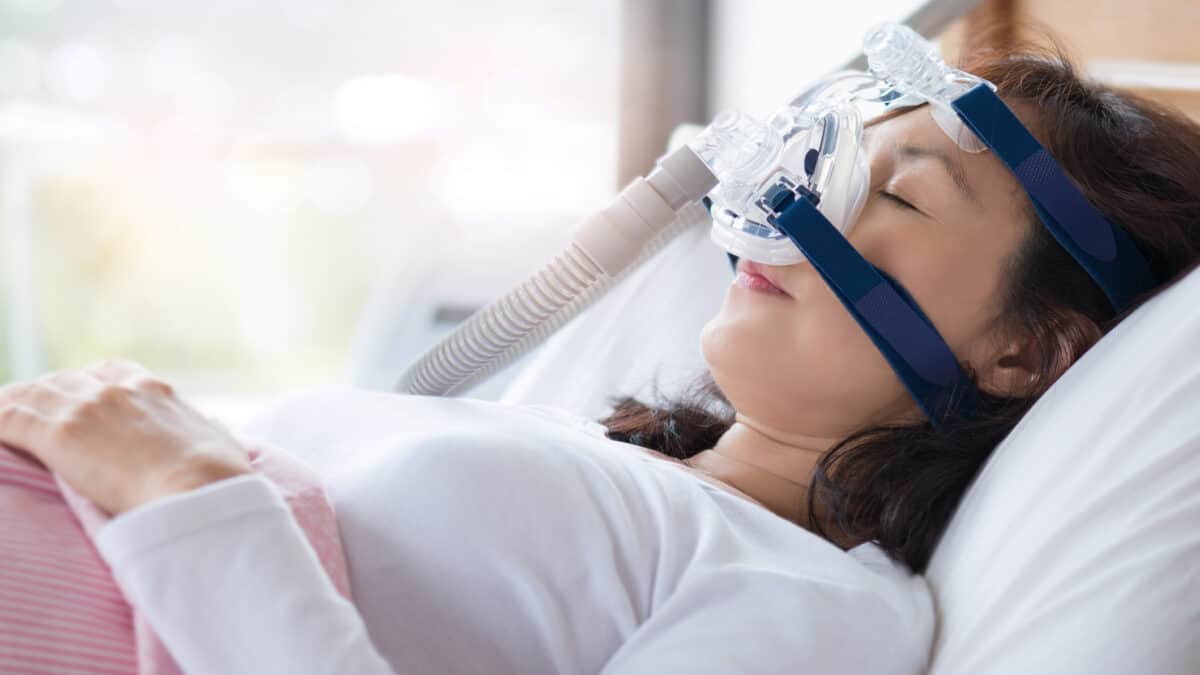
Senior woman using cpap machine to stop choking and snoring from obstructive sleep apnoea with bokeh and morning light background.

Image source: Getty Images

What's driving growth in ResMed shares

ResMed's business success in 2024 is underpinned by its growing demand for obstructive sleep apnoea (OSA) products.

The company reported a 12% lift in revenue, reaching $4.7 billion for FY24, and produced $1.3 billion in free cash flow. As I've mentioned previously, that means for every dollar of revenue, 27.7 cents went straight to free cash flow.

One talking point was ResMed's myAir app, which saw patient enrolment rise by 28% year over year.

But it's not just the numbers that have investors piling into ResMed shares.

ResMed operates in a significantly underpenetrated market for OSA, of which there are an estimated 1 billion sufferers globally.

It has a dominant position in this market following the recall of Philips' competing line of continuous positive airway pressure (CPAP) machines, which are used to manage OSA.

What are analysts projecting for 2025?

Looking forward, analysts have high hopes for ResMed. According to CommSec, the consensus of analyst estimates rates it a buy.

Consensus estimates also forecast the company's earnings to grow 20% between FY25 and FY27, with a potential earnings per share (EPS) of $1.54 by the latter year.

Ord Minnett is also bullish, rating ResMed as a buy with a price target of $40.05.

The broker highlighted ResMed's strong September quarter, where revenue grew 11%, and EPS surged by 35%.

It forecasts the company to grow EPS by 13% in 2025, "which justifies its current trading multiples". ResMed trades on a price-to-earnings (P/E) ratio of 32x at the time of writing.

Meanwhile, US-based investment firm Baird also rates ResMed as a buy, citing the increasing prevalence of obstructive sleep apnoea (OSA) as a key driver.

However, it flagged concerns about potential competition from GLP-1 weight-loss drugs, which could reduce the prevalence of OSA.

Baird set a price target of US$280 for ResMed's US-listed shares, which currently sit at US$239 apiece, more than 17% upside potential.

Foolish takeout

ResMed shares are rated favourably heading into 2025. Brokers on aggregate say its a buy, and the general consensus is for reasonably strong growth next year.

In the last 12 months, Resmed is up 49%.

Motley Fool contributor Zach Bristow has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended ResMed. The Motley Fool Australia has positions in and has recommended ResMed. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Healthcare Shares

Doctor looks at a graph on a tablet.
Healthcare Shares

Ramsay Health Care vs Sonic Healthcare: Which healthcare stock is better value?

Which offers better value — Ramsay Health Care or Sonic Healthcare? I compare their fundamentals, dividends, momentum and reveal my…

Read more »

A doctor looks unsure.
Healthcare Shares

CSL shares jump 93%: Is the ASX biotech stock a buy, sell or hold for October?

Can the CSL share price rebound keep going?

Read more »

Two doctors having a discussion about a patient diagnosis, holding digital tablet.
Healthcare Shares

Are CSL shares a buy after its big news?

I look at what CSL’s latest drug development deal could mean for the healthcare giant’s long-term growth.

Read more »

A female scientist in a laboratory setting using a tablet to review data, with a male scientist working in the background.
Healthcare Shares

ResMed vs Fisher & Paykel Healthcare: Which is better value?

How do ResMed and Fisher & Paykel compare on value, income, and share price momentum? Here’s my verdict on which…

Read more »

Happy doctor using her laptop.
Healthcare Shares

CSL unveils exclusive Alentis deal to advance rare disease treatments

CSL unveils a major partnership for rare disease drug development, enhancing its global nephrology strategy.

Read more »

Doctor sees virtual images of the patient's x-rays on a blue background.
Healthcare Shares

Could this ASX biotech really jump more than 80% in value?

This company's new technology has one broker impressed.

Read more »

Teamwork, planning and meeting with doctors and laptop for medical, review and healthcare. Medicine, technology and internet with group of people for collaboration, diversity and support in hospital
Healthcare Shares

CSL vs Pro Medicus: Which ASX healthcare share is better?

Both CSL and Pro Medicus have faced recent challenges but have enviable long-term track records. Here's which one I'd buy…

Read more »

Scientists working in the laboratory and examining results.
Healthcare Shares

This ASX biotech could rise almost 50%, Morgans says

Turning science into contracts could unlock value for this company.

Read more »







