Having a few simple rules is a great way to keep you focused when investing.
But rules, as they say, are only for the guidance of wise men.
Motley Fool co-founder David Gardner runs the Motley Fool (U.S) 'Rule Breaker' investing service and looks for six simple, but crucial, characteristics when hunting for long-term winning companies, some of which break common investing wisdom.
So how does rapidly growing online financing company Afterpay Touch Group Ltd (ASX: APT) compare to Gardner's six 'Rule Breaker' criteria?

1. A "top dog", "first mover" company in an important, emerging industry
Gardner's first criteria fit Afterpay nicely. The availability of finance options for online shopping is still in its infancy and Afterpay was an early mover in developing an effective platform that benefits both shoppers and retailers.
Afterpay has moved rapidly to grab market share and boasts the largest portfolio of leading brands in Australia and New Zealand.
2. Holding a sustainable advantage
A sustainable advantage, says Gardner, can be gained through "business momentum, patent protection, visionary leadership, or inept competitors". The payments space is rife with competition with local competitors including LayBuy, OxiPay, operated by FlexiGroup Limited (ASX: FXL), and ZipPay, operated by Zip Co Ltd (ASX: Z1P), gunning for the same market.
However, as an early mover Afterpay could build significant network advantages: winning big-name retail partners draws more customers which allows Afterpay to pitch a larger number of prospective consumers to win new retailers. It's a virtuous cycle.
3. Strong past share price appreciation
Here is where traditional investing rules start to go out the window. David Gardner's 'rule breaker' criteria look for companies which have a history of strong upward share price momentum. In Gardner's own words "We think the winners generally keep on winning."
In mid-2017, when Afterpay merged with TouchCorp, the business group had a joint, fully diluted, market capitalisation of around $700 million. Today the company is up almost five times that with a market cap of over $4 billion. Tick.
4. Good management and smart backing
I admit I don't know a lot about After-pay co-founders Anthony Eisen and Nick Molnar (also CEO). This would warrant a closer look, but their success to date suggests visionary leadership with a history of delivering on the aggressive goals.
5. Strong consumer appeal
Strong consumer appeal is about giving customers a positive experience to generate repeat business.
Afterpay's service appears to be rapidly gaining favor with consumers for its ease of use while increasing sales for retailers, adding value on both sides.
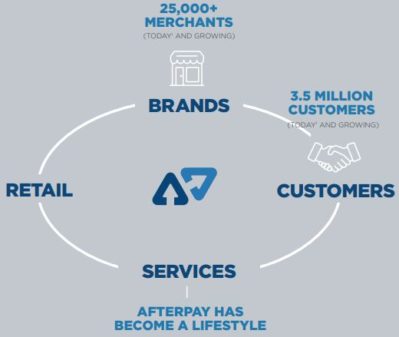
Source: Afterpay Touch 1H19 results presentation
6. Documented proof that the stock is considered overvalued according to the financial media
Gardner's final point, similar to number three, goes against conventional investing wisdom. Being labelled over-priced, he argues, is less relevant if the other five 'rule breaker' characteristics ring true because great, long-term companies regularly command high valuations. Gardner cites Amazon as an example which was labelled 'over-valued' back in 2000. Since then Amazon shares are up over 6,500%.
A quick web search for "Afterpay overvalued" yields mostly scrappy, conjecture filled investment forums. There is certainly the occasional 'eye-wateringly expensive' type comment, but it seems that most people recognise that there is a vast opportunity ahead if Afterpay can fend off competitors and regulators to win in overseas markets.
So, is it a 'rule breaker'?
Based on Gardner's six criteria I think Afterpay would sit high on the spectrum of potential 'Rule Breaker' investments.
However, there can be higher risks to owning highly valued, cash-burning companies and certainly less margin for error if expectations are not met so I would be cautious with the size of any position I added to my portfolio today.