Last week was a tough week for BHP shares.
BHP Group Ltd (ASX: BHP) has spent two decades trying to prove it can be more than an iron ore and copper company.
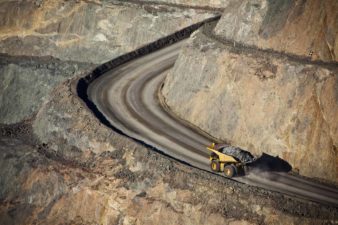
Jansen, its giant potash project in Saskatchewan, Canada, is the clearest test of that ambition.
This week, that test got harder.
BHP shares fell 3.20% on Friday to $62.96 after the company revealed another cost blowout at Jansen. The stock has now fallen approximately 8% from its 52-week and record high.
Image source: Getty Images
What actually happened at Jansen
BHP completed a detailed review of the cost and schedule estimates for Jansen Stage 2, and the news was not good.
The company now expects Stage 2 to cost between US$4.9 billion and US$5.4 billion more than previously estimated. This is on top of an original sanctioned budget of US$4.9 billion approved back in October 2023.
BHP will recognise an impairment charge of about US$2.3 billion against Jansen Stage 2 as part of its FY26 results.
First production from Stage 2 is now targeted for FY2031, a delay from the originally planned 2029 start.
Stage 1, separately, remains on track for first production in FY2027, though its cost estimate has also crept higher since being sanctioned.
BHP has confirmed it will provide a further update on Stage 1 timing and spending before 31 December 2026.
Why the market reacted so sharply
An impairment charge of this size is, by definition, a non-cash accounting adjustment rather than an immediate cash outflow.
But it is also a credibility issue.
This is not the first time Jansen's costs have risen beyond what was originally promised. Each successive upward revision makes the market more sceptical of management's next set of project projections.
BHP shares had already gained around 35% since the start of 2026. This has left little margin for disappointment once the news landed.
Does this change the long-term investment case for BHP shares?
Jansen represents BHP's attempt to diversify beyond iron ore and copper into a third major commodity pillar tied to global food security and agricultural productivity.
Management still sees potash as an important long-term growth area despite the cost overrun. The company has explicitly framed this week's update as a matter of timing and cost rather than an abandonment of the underlying strategy.
That framing matters for how investors should weigh the news. The setback is real, but BHP is not signalling that it is walking away from potash altogether.
Why BHP shares could still be a buy
The case for BHP shares has never rested primarily on Jansen.
BHP's growing copper exposure, combined with rising global demand for electricity-intensive infrastructure, including data centres, electric vehicles, and renewable energy, remains the stronger near-term driver of the company's earnings and dividend.
The current pullback to approximately 9% below the record high gives investors a more reasonable entry point into a business whose iron ore cash generation and copper growth trajectory have not been altered by this week's news.
Jansen still adds a longer-term potash option, even with a delayed timeline, rather than removing a pillar of the investment case entirely.
Foolish takeaway
BHP's bet beyond iron ore just got more expensive and will take longer to pay off than originally promised.
That is a setback, and the market's sharp reaction reflects real concern about capital discipline at BHP.
But the core reasons to own BHP shares: scale, a strong iron ore cash engine, and growing copper exposure tied to the AI and electrification megatrend, remain firmly in place.
For investors who can accept that mega-projects rarely run exactly to plan, the post-Jansen pullback may offer a reasonable entry point rather than a reason to walk away.