After rising 22% this month, it could be time to sell this booming ASX materials stock

It could be time for investors to find the exit after a red hot start to the year.

Stanmore Resources Ltd (ASX: SMR) has been one of the best ASX materials stocks to own in 2026. 

Since the start of the year it has risen an impressive 22.08%. 

For context, the S&P/ASX 200 Index (ASX: XJO) is up 2.36% in the same period. 

However, yesterday this ASX materials stock fell 2.33%. 

This was despite reporting a record December quarter coal production and strong cash generation on January 27.
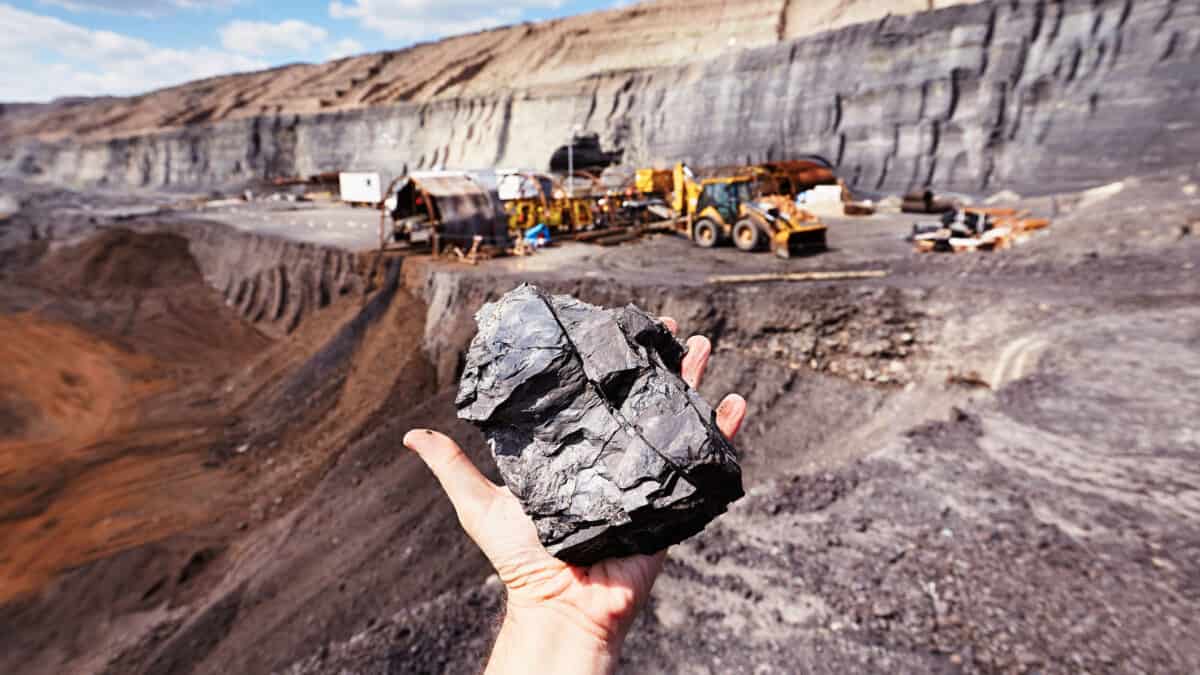
Hand holding out coal in front of a coal mine.

Image source: Getty Images

Investor sell-off  

Stanmore Resources is an Australian coal producer with operations and exploration projects in the Bowen and Surat Basins in central and southern Queensland.

It is one of Australia's largest suppliers of metallurgical coals to global markets with three major assets including the Isaac Plains complex and the Poitrel and South Walker Creek coal mines.

Stanmore also has a 50% ownership stake in the Millennium and Mavis Downs mines.

Its most recent quarterly report included: 

  • Record quarterly run-of-mine (ROM) coal production of 6.0 million tonnes (Mt), saleable production of 3.9Mt, and sales of 4.0Mt
  • Full-year saleable coal production of 14.0Mt.
  • Net debt reduced by US$57 million in Q4
  • Total liquidity climbed to US$482 million at 31 December 2025
  • Serious Accident Frequency Rate for the year was 0.33, significantly below industry benchmarks
  • Average sales price achieved was US$133 per tonne, with a late-quarter rally in coal markets

Despite these results, investors have been trimming their positions in this ASX materials stock over the last couple of days. 

The stock price has dropped almost 4% since Tuesday's open. 

What's Morgans' view?

The team at Morgans have provided fresh guidance for this ASX materials stock following its quarterly results. 

The broker highlighted that Stanmore Resources delivered record quarterly results in 4Q25 across run-of-mine (6.0Mt), saleable product (3.9Mt) and product sales (4.0Mt) whilst dealing with unseasonably high rainfall.

Increased sales helped operational cash flow that saw total cash increase to US$212m and net debt reduced by US$57m to US$33m. 

Morgans said the Isaac Downs site is expected to deliver materially lower output in 2026 as mining progresses deeper into the pit and approaches less economic zones. 

Poitrel's production is also forecast to ease after a standout 2025 performance. 

Based on this guidance, Morgans has downgraded its recommendation to TRIM. 

It also has a revised target price of $2.95ps. 

It would appear based on this target that this ASX materials stock is fully valued, after closing yesterday at $2.93 per share. 

Our target for SMR is set at a discount to NPV to reflect opacity in the short-term coal price outlook.
Motley Fool contributor Aaron Bell has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Materials Shares

A woman draws on a clear screen a graph that shows a falling horizontal line.
Materials Shares

ASX lithium shares take a hit amid 20% fall in lithium price

The lithium carbonate price has fallen nearly 20% over the past month.

Read more »

Two colleagues working with company financial results.
Materials Shares

Zimplats: September 2026 quarterly earnings

Zimplats reports steady progress on major projects despite a dip in quarterly output.

Read more »

A couple cheers as they sit on their lounge looking at their laptop and reading about the rising Redbubble share price
Materials Shares

PLS Group is making a $1.9 billion bet on lithium. Should investors follow?

I take a closer look at what this expansion could mean for shareholders.

Read more »

a female steel worker wearing a high visibility vest with her protective helmet tucked under her arm smiles as she carries a clipboard in a large warehouse of steel products.
Materials Shares

BlueScope upgrades first-half FY2027 earnings guidance

BlueScope has upgraded its 1H FY2027 earnings guidance, with underlying EBIT now expected to approach $1.1 billion.

Read more »

A small child in a sandpit holds a handful of sand above his head and lets it trickle through his fingers.
Materials Shares

Why have Lynas Rare Earths crashed 42% in 6 months?

The shares are also down 7% for the year to date.

Read more »

Two business men looking at financial data, charts, and graphs on a digital tablet and a laptop computer.
Materials Shares

Alcoa posts higher net income, sets sights on AliGroup completion

Alcoa reported third quarter 2026 results, with higher net income and progress on the AliGroup acquisition.

Read more »

A woman sits in a cafe wearing a polka dotted shirt and holding a latte in one hand while reading something on a laptop that is sitting on the table in front of her
Materials Shares

Orora FY26 earnings: Cans strong, Glass under pressure

Orora's FY26 results show strength in Cans but ongoing challenges for Glass, including a substantial non-cash impairment.

Read more »

Three people at a building site discussing a plan whilst eating.
Materials Shares

Fletcher Building posts higher volumes in Q1 FY27, residential lags

Fletcher Building posted Q1 FY27 sales volume growth in several key business units, though residential activity stayed challenging.

Read more »