Some ASX shares stand out because they operate in markets that are becoming increasingly important over time. Others earn attention because their technology addresses a problem that simply isn't going away.
DroneShield Ltd (ASX: DRO) does both.
It operates in a niche that is becoming mission-critical, supported by technology that is difficult to replicate and growing more relevant by the year. While history shows that its share price will likely remain volatile, my focus is on the long-term opportunity this business is chasing, and one that I believe could play out over many years.
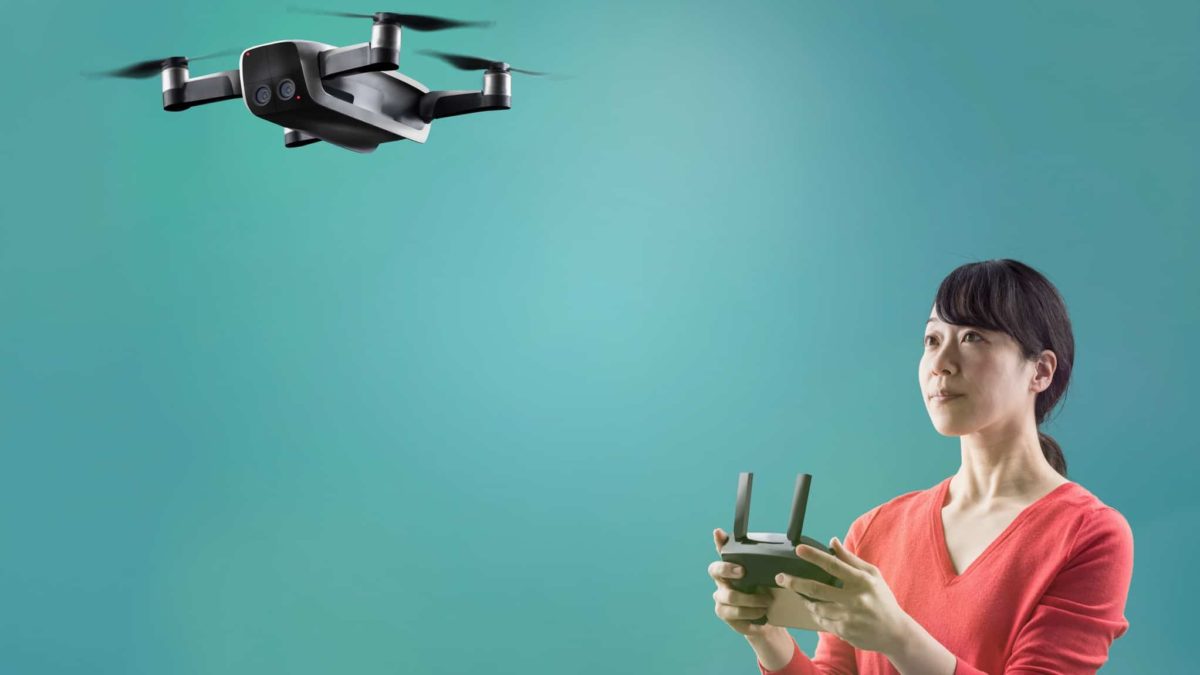
Image source: Getty Images
A problem that isn't going away
Drones are no longer just toys or tools for hobbyists. They've become a genuine security threat across military operations, government facilities, airports, prisons, critical infrastructure, and even major public events.
That's where DroneShield comes in.
The company develops counter-drone solutions designed to detect, track, identify, and neutralise unauthorised drones. It does this using a mix of radio frequency sensing, artificial intelligence (AI), radar, optical systems, and electronic warfare. As drone technology becomes cheaper, more capable, and more widely available, the need for effective counter-drone systems is only growing.
Importantly, this isn't a cyclical issue. Governments and defence agencies don't get the option to wait it out when it comes to protecting sensitive assets. Security threats don't disappear just because economic conditions soften.
Defence spending provides powerful tailwinds
One of the key reasons I'm comfortable owning DroneShield shares is the broader environment it operates in. Global defence spending is trending higher, not lower.
Geopolitical tensions, asymmetric warfare, and the changing nature of conflict have pushed counter-drone capabilities up the priority list for many countries. There's even talk of a drone wall across Europe's eastern border. DroneShield already counts military and government agencies among its customers and continues to secure contracts across allied nations.
These relationships matter. Defence procurement tends to involve long sales cycles, high barriers to entry, and meaningful switching costs once systems are deployed. Over time, that creates the potential for repeat orders and more predictable revenue, even if contract announcements arrive unevenly.
A platform with room to scale
Another reason I like DroneShield is that it's not a one-trick pony. Its technology is modular and heavily software-driven, which allows it to evolve alongside emerging drone threats.
As the installed base grows, there's an opportunity to sell higher-margin software upgrades, updates, and ongoing support. If management executes well, I think that operating leverage could eventually help transform DroneShield from a lumpy, contract-driven business into a more consistently profitable defence technology company.
Why I'm comfortable holding through volatility
There's no denying DroneShield shares can be volatile. Contract timing, government budgets, and market sentiment can all send the share price swinging.
But I'm comfortable with that. History shows that long-term returns are often earned by holding high-quality businesses through short-term noise. DroneShield operates in an expanding market, its technology is already proven, and its strategic relevance appears to be increasing, not fading.
Foolish Takeaway
I'm buying and holding DroneShield shares because the world is becoming more complex, not less. As long as drones remain a threat, counter-drone solutions will remain essential.
For patient investors willing to look past near-term volatility, I believe DroneShield could be a top long-term buy.