This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.
The stock market cares more about future earnings potential than the past -- and that may be why Nvidia, Microsoft, Apple (NASDAQ: AAPL), and Amazon (NASDAQ: AMZN) are all worth more than Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) today even though Alphabet is the only S&P 500 stock with over $100 billion in trailing-12-month net income.
Here's why the market views Alphabet's earnings differently than other megacap growth stocks, and whether Alphabet is a buy now.
More than just a number
Earnings are one of the most important metrics investors use to value a company. How much profit a company generates is an integral part of an investment thesis. But so are expectations for future profits.
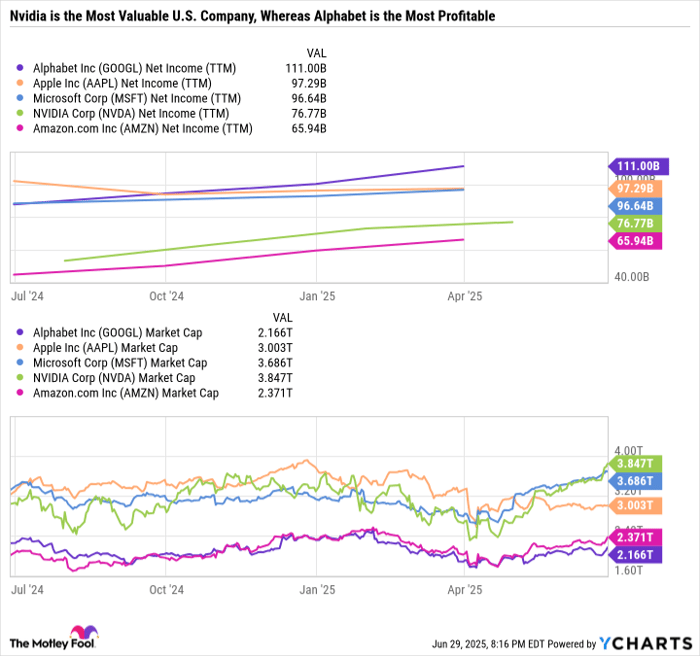
GOOGL Net Income (TTM) data by YCharts
Although net income is just a number, there are nuances worth understanding. A leading company that operates in a growing industry with competitive advantages, high profit margins, and a great balance sheet will have far higher-quality earnings than a company operating in a declining or even failing industry that is cyclical and capital-intensive.
This concept is why even the best oil and gas companies, like ExxonMobil and Chevron, sport such inexpensive valuations. Their earnings aren't high-margin. Generating them takes a lot of capital. And oil and gas consumption may look much different decades from now than today. This doesn't mean ExxonMobil and Chevron are bad companies. In fact, both are excellent dividend stocks. It just means investors are unlikely to pay the same price for these companies relative to their earnings as, say, an ultra-fast-growing company with high margins like Nvidia.
Alphabet doesn't have a capital-intensive business model. It generates high margins and has diverse revenue streams from its services like Google Search, Google Network, YouTube, Android, Google Cloud, and more. It also has a phenomenal balance sheet with more cash, cash equivalents, and marketable securities than debt. Despite these advantages, Alphabet sports a price-to-earnings (P/E) ratio and forward P/E ratio that are far lower than Nvidia, Microsoft, Apple, and Amazon.

NVDA PE Ratio data by YCharts
Expectations drive valuations
This discounted valuation is why Alphabet is worth less than its peers despite making more profit. Alphabet's valuation is much cheaper than some of its peers because investors are less optimistic about its future earnings prospects.
Nvidia is powering the future of artificial intelligence (AI) with its graphics processing units for data centers. Big tech continues to spend on AI, so investors are optimistic that demand for Nvidia's products will continue growing.
Microsoft is integrating AI into its software and is the No. 2 player in cloud computing behind Amazon. In contrast, Alphabet's Google Cloud is a distant third in market share.
Apple isn't growing quickly, but the company has such a dominant, vertically integrated ecosystem of consumer products and services that investors are willing to pay a premium price for the stock relative to its earnings.
Alphabet makes the majority of its operating income from Google Search. Unlike Amazon (and arguably Microsoft), cloud is not the most valuable aspect of the company. Alphabet's AI plays mainly come from Google Cloud and its "Other Bets" category, which consists of projects like self-driving company Waymo and AI research lab DeepMind, which is behind the chatbot Gemini.
In sum, the market may be viewing Alphabet's business model as more vulnerable to technological advancements in AI than other megacap growth companies that are clearly benefiting from AI.
Alphabet is an impeccable value
There's a famous (and still relevant) quote by Warren Buffett that goes, "You pay a very high price in the stock market for a cheery consensus." Companies that are favorable to many investors tend to demand expensive valuations, whereas companies with an element of uncertainty can fetch a discount.
The simplest reason to buy Alphabet right now is if you believe the market's skepticism about the company's AI potential is unwarranted or overblown. In that case, investors can buy Alphabet at a steep discount to its peers. If Alphabet had a 30 P/E ratio instead of a sub-20 P/E, it would be worth well over $3 trillion. If it had Microsoft's P/E, it would be the most valuable company in the world.
In many ways, Alphabet deserves to trade at a discount to these other big tech names. But maybe only by a little bit -- not the drastic discrepancy we are seeing in the market today. All told, now is a great time for value investors interested in big tech to buy Alphabet stock.
This article was originally published on Fool.com. All figures quoted in US dollars unless otherwise stated.