
Down 20% this year, are Whitehaven Coal shares a buy, hold or sell according to Macquarie?

Here's what's in store for this Australian independent coal producer.

Whitehaven Coal Ltd (ASX: WHC) engages in the development and operation of coal mines. It operates six mines across NSW and QLD, producing metallurgical coal that's critical for steelmaking and thermal coal.

It has endured a tough year to date, falling 21.34% since the start of 2025 and more than 35% in the last 12 months. 

For context, the S&P/ASX 200 Energy Index (ASX: XEJ) is down roughly 17% since the start of 2025 and 28.16% over the past year. 

Coal mining companies and energy shares have had a rough start to the year in general on the back of weak commodity prices and tariff uncertainty.
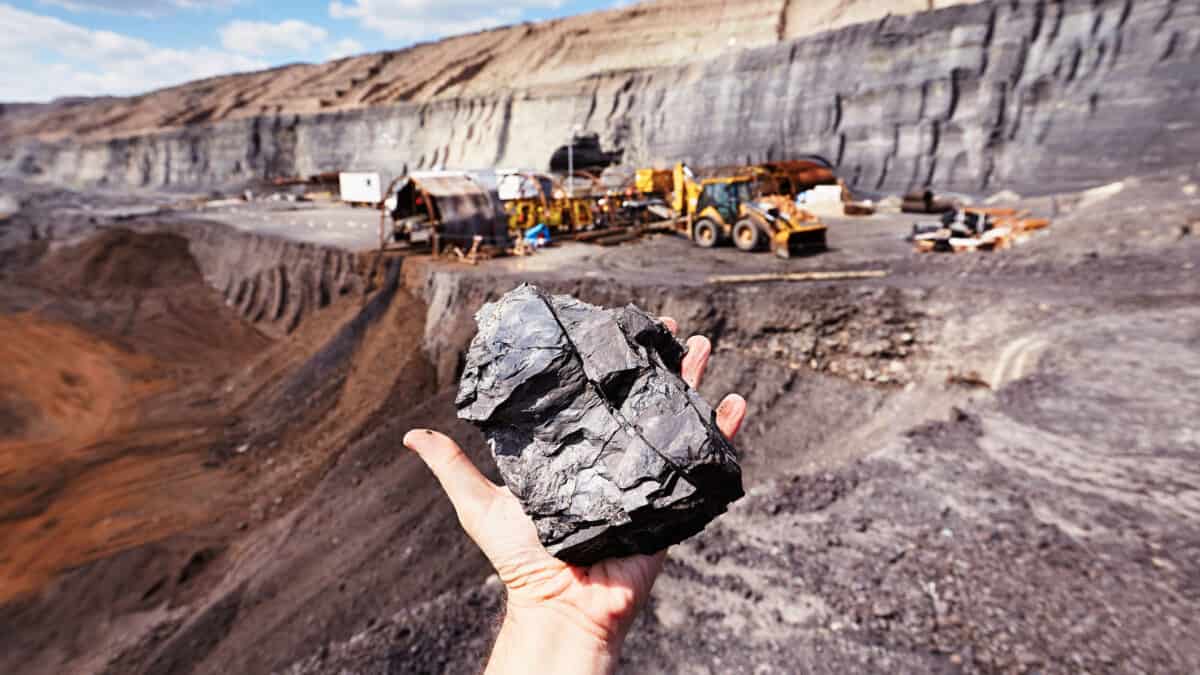
Hand holding out coal in front of a coal mine.

Image source: Getty Images

What is Macquarie saying about Whitehaven Coal?

In a report released this week by Macquarie, the broker said the dividend could be under pressure due to negative EPS projections for 2HFY25. 

According to Macquarie, one positive from the company is that: 

Despite wet weather across NSW and QLD, WHC beat consensus in QLD in both ROM and Saleable Coal (SP) (+7%/ +11%) and NSW (+17%/+24%). Blackwater was the key performer, beating consensus +11%/+17% on ROM/SP.

However, there were some negative results out of Whitehaven's Queensland locations. 

QLD realised pricing again missed our estimates with our lagged pricing formula (~3 months) implying low-80% realisations vs 77% actual, which eroded the solid sales result.

The result of the report was a "neutral" rating on the company and a 12-month price target of $5.50.

Based on the current share price of $4.94, this price target implies a 11.34% upside. 

What are other brokers saying?

Earlier this month, Goldman took off its buy rating on Whitehaven Coal shares and downgraded them to neutral with a $5.70 price target.

A report from broker Bell Potter earlier this month had a more optimistic view on the future of Whitehaven Coal shares. The broker said: 

WHC's balance sheet has significantly de-risked and its Queensland operational outlook continues to strengthen, ensuring greater resilience to withstand current weaker coal markets. We have a positive long-term met coal outlook and see an increasingly consolidated supply base.

The Bell Potter price target is currently $7.40. 

Online brokerage platform SelfWealth sits between with an average price target of $6.60.
Motley Fool contributor Aaron Bell has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended Goldman Sachs Group and Macquarie Group. The Motley Fool Australia has positions in and has recommended Macquarie Group. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Energy Shares

A woman wearing a black and white striped t-shirt looks to the sky with her hand to her chin, contemplating buying ASX shares.
Energy Shares

Boss Energy vs Paladin Energy: Which ASX uranium stock wins?

Boss Energy and Paladin Energy are ASX uranium leaders. Here’s which I’d buy based on value, growth, and latest performance.

Read more »

A mining worker clenches his fists celebrating success at sunset in the mine.
Broker Notes

Macquarie says this ASX uranium producer has more than 15% upside

A new mine design has impressed the broker.

Read more »

A service station attendant crosses his arms and smiles towards the camera with a backdrop of petrol bowsers and a drive-through facility.
Energy Shares

Woodside vs Ampol: Which ASX energy stock should you buy?

Woodside and Ampol both offer franked dividends and momentum—so which ASX energy stock wins out on value and yield?

Read more »

Woman sitting on a chair by the pool on her laptop, looking at a stock market chart.
Energy Shares

Origin Energy vs AGL Energy: Which ASX dividend stock is better for income?

Origin and AGL are both strong dividend payers—but I think Origin has the edge for income investors right now.

Read more »

Frustrated man looking exhausted while sitting at his desk with his laptop and carrying his glasses in his hand.
Energy Shares

Guess which ASX 200 stock was downgraded to a sell rating

Bell Potter is bearish on this stock. Here's what it is saying.

Read more »

An oil worker assesses productivity at an oil rig.
Energy Shares

Santos vs Woodside: Which ASX energy share is better value?

The numbers reveal a clear value winner between Santos and Woodside shares right now.

Read more »

Worker inspecting oil and gas pipeline.
Energy Shares

Here's the earnings forecast out to 2028 for Woodside shares

Will Woodside’s earnings grow with strong energy prices in the years ahead?

Read more »

Lakes in the form of footsteps among the green trees, indicating steps towards a healthier planet.
Energy Shares

Contact Energy reports higher sales and renewable project progress in August

Contact Energy lifted energy sales in August 2026 and progressed big renewable projects.

Read more »







