Lovisa Holdings Ltd (ASX: LOV) stock is a really attractive investment to me for both its dividends and growth. The S&P/ASX 200 Index (ASX: XJO) share has plenty of pleasing characteristics, which I'll explore in this article.
Lovisa sells affordable jewellery to younger shoppers.
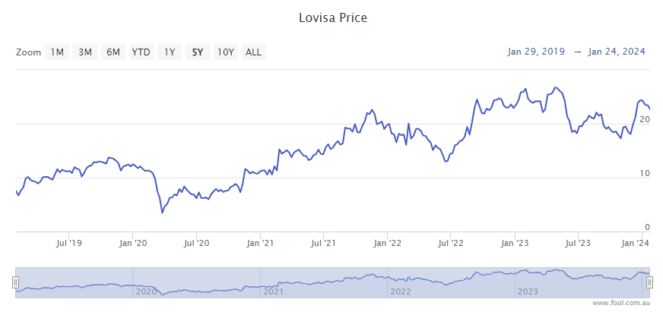
Image source: Getty Images
Strong profitable growth
Investors often like to judge a company based on profit and how much it's expected to make. In FY23, on a 52-week comparative basis, Lovisa grew net profit after tax (NPAT) by 20.1% to $68.2 million.
A key part of Lovisa's growth (and that of almost any ASX 200 share) is revenue growth. Store count growth is a large driver of revenue growth. In FY23, Lovisa's revenue rose by 33.1% on a 52-week basis, and the store count grew by 27% (or 172 stores) to 801 stores.
A lot of those new stores have been open for less than a year, so a full 12 months of operations will add to revenue and profit. Opening a new store or entering a new country comes with costs before any revenue flows in. It's an upfront investment but well worth it.
Lovisa entered a number of new markets in FY23, including Hong Kong, Taiwan, Namibia, Botswana, Spain, Italy, Hungry, Romania, UAE and Mexico. In FY24, it's entering markets like China and Vietnam. The longer the growth runway, the more it can help Lovisa stock.
At the end of FY23, it had 195 stores in Australia and New Zealand out of a global total of 801.
The company could open a significant number of potential stores in the next decade.
For now, I'm just working on the premise that Lovisa can roughly double its store count over the next five years. This could boost its revenue and profit by roughly double, particularly if operating leverage can help with its growing store count. This would then be very supportive of Lovisa's stock price, in my opinion.
Great dividends
If revenue and profit can continue to grow at the rate I think it might, there could be a lot of scope for the dividend to keep growing if it sticks to the same dividend payout ratio.
I'd expect capital growth to make up the larger portion of overall returns over the long term from this ASX 200 share. But the dividends are a welcome boost, particularly if we don't want to sell any shares and still benefit from the profit growth.
In FY23, the company paid an annual dividend per share of 69 cents. That translates into a trailing cash yield of 3% and a grossed-up dividend yield of around 4%.
The dividend may not be as strong in FY24 based on the current retail conditions, but by FY26, it could pay an annual dividend per share of 91 cents (according to Commsec). This would be a potential cash yield of 4% or a grossed-up dividend yield of more than 5%.
At the current Lovisa stock price, I'd be happy to buy some shares for the long term and top up on any sell-offs.