Fortescue Ltd (ASX: FMG) shares are trading in the green on Tuesday morning. At the time of writing, the shares are up 1.7% to $20.60 a piece.
The latest uptick means the shares have now climbed 8.3% over the past month, although they're still down 7% for the year to date.
For the year, the shares are 43.7% higher.
It's been a volatile start to the year for Fortescue shares, so if you're thinking of adding the stock to your portfolio, here are some things to consider.
Image source: Getty Images
3 reasons to buy Fortescue shares
1. Attractive dividend yield
Because the miner is a low-cost producer, meaning it can remain profitable even when iron ore falls, it is able to pay a reliable dividend to investors. Fortescue is a popular high-yielding dividend-paying stock. Broker UBS predicts that Fortescue could pay an annual dividend per share of $1.22. At the time of writing, that translates into a grossed-up dividend yield of just over 5.92%, including franking credits.
2. Copper exposure
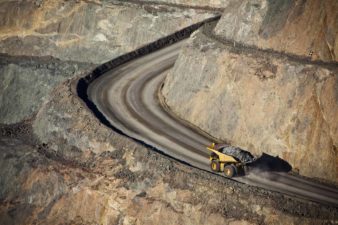
Fortescue is primarily an iron ore miner but it is actively expanding in the copper space. Not only will that give the miner more diversity and less reliance on the iron ore market, it could also give long-term operational upside. If its copper exposure keeps growing it would help support overall earnings.
3. Expansion and growth
Fortescue is continually investing in business expansion. Not only is the miner planning to grow its copper exposure, it is also focused on building significant renewable energy infrastructure, decarbonisation and expansion of its green energy projects, and developing and expanding its existing iron ore sites to improve production efficiency. These projects are positive for long-term profitability.
3 reasons to sell Fortescue shares
1. Heavily tied to iron ore prices
While Fortescue has a copper footprint, the miner primarily mines and exports iron ore. This means it is heavily reliant on the price of iron ore and is subject to any price fluctuations that the material might have. The price of iron ore is expected to soften through 2026 and then gradually decline through to 2030 as supply increases and Chinese steel demand tapers off.
2. The shares are overpriced
Fortescue's share price is looking overvalued right now. While its current price-to-earnings (P/E) ratio of 11.54 looks attractive on the surface (the average P/E ratio within ASX metals and mining companies is anywhere between 12.5 and 25), it doesn't take into account projected declines in earnings. UBS forecasts that the business will earn US$3.8 billion in net profit in FY26, but this is expected to drop to US$2.94 billion in FY27 off the back of lower iron ore prices.
3. Brokers rate the stock as a sell
Analysts are mostly bearish on Fortescue shares. TradingView data shows that nine out of 17 analysts have a hold rating on the stock, and another seven have a sell or strong sell rating. The average 12-month target price of $20.02 implies a potential 1.1% downside at the time of writing.