The Cochlear Ltd (ASX: COH) share price has struggled to regain momentum after a difficult year.
The ASX healthcare stock finished Friday down 0.3% at $263.24. That is above its late-December low, but the shares are still about 13% lower than a year ago. By comparison, the S&P/ASX 200 Index (ASX: XJO) has climbed almost 5% over the same period.
That gap highlights how much Cochlear has underperformed the market, despite remaining one of Australia's most respected healthcare businesses.
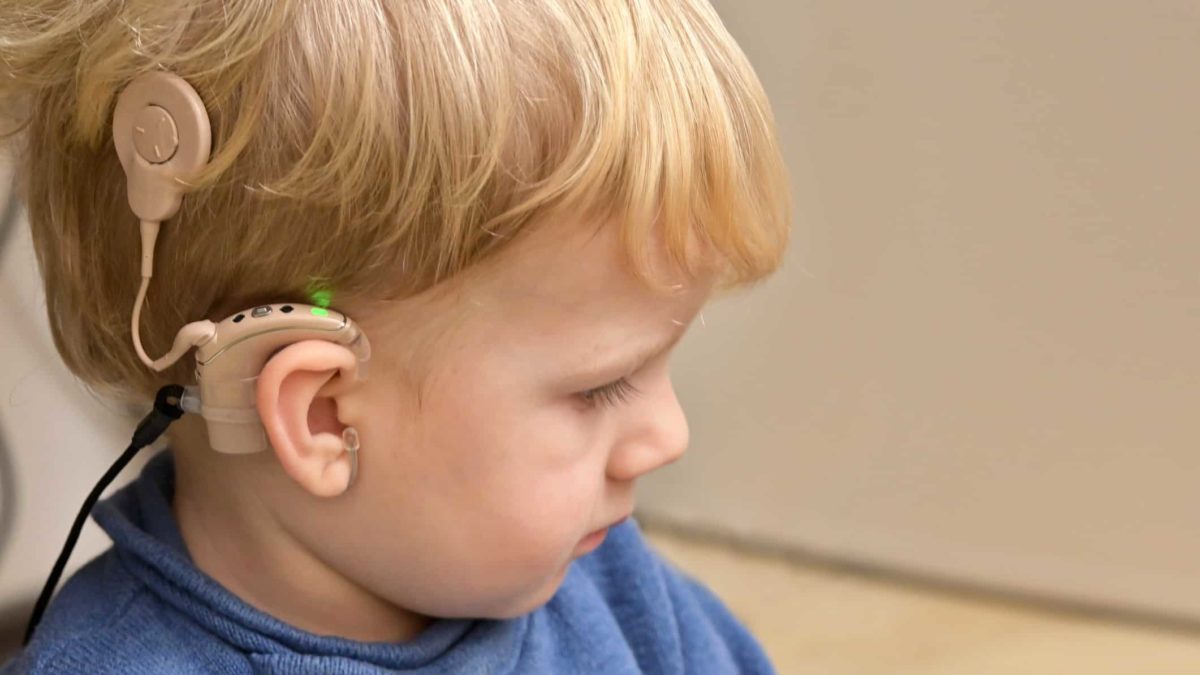
Image source: Getty Images
A high-quality business, but returns have disappointed
Cochlear remains one of the world's leading hearing implant companies. It has a strong brand, proven technology, and a large base of existing patients who return for follow-up services over time.
That has delivered steady revenue and solid margins for many years. The long-term outlook also remains solid, supported by ongoing demand for hearing implants and regular product development.
Over the past year, however, investors have become less willing to pay a premium for slower-moving growth companies. With earnings momentum moderating, Cochlear shares have struggled to keep pace with faster-growing or more cyclical stocks.
Valuation is holding the shares back
One key reason Cochlear shares have lagged is because of its valuation.
The stock trades on a price-to-earnings ratio (P/E) of about 44. That means investors are paying $44 for every $1 the company earns, which is much higher than most other ASX healthcare stocks.
That premium was easier to justify when growth was stronger. With profit growth slowing and investors becoming more selective, interest has shifted toward cheaper stocks or companies delivering faster earnings growth.
What management is saying
At its recent AGM, management said the business continues to grow and invest for the future.
In FY25, Cochlear reported revenue of $2.36 billion and underlying net profit of $392 million. The total dividend for the year rose by 5% to $4.30 per share.
Looking ahead, management expects underlying net profit in FY26 to come in between $435 million and $460 million, implying growth of roughly 11% to 17%. That outlook is being driven by demand for new implants, new product launches, and continued investment in research and development.
Foolish bottom line
Cochlear shares have lifted from their December low, but remain well below last year's levels.
That reflects more cautious investor sentiment rather than any major issue with the business. Growth has slowed, the valuation remains high, and the market is waiting for stronger earnings momentum before becoming more positive again.
I'd prefer to wait until the company releases its interim results next month before jumping in.