Is now the time to buy Pro Medicus shares?

After a 13% pullback, Pro Medicus shares are back in focus. Is this weakness an opportunity?

| More on:

You’re reading a free article with opinions that may differ from The Motley Fool’s Premium Investing Services. Become a Motley Fool member today to get instant access to our top analyst recommendations, in-depth research, investing resources, and more. Learn More

Key points
  • Stable Business Fundamentals: Despite a recent 13% share price decline, Pro Medicus remains fundamentally strong with no adverse changes in its operations or loss of major contracts.
  • Continued Contract Growth: Recent long-term contract wins and an expanding footprint in US hospital networks demonstrate Pro Medicus's robust market position and growth potential.
  • Positive Broker Outlook: Major brokers maintain bullish ratings, emphasizing its long-term growth trajectory and significant upside potential, highlighting the pullback as a potential buying opportunity.

The Pro Medicus Ltd (ASX: PME) share price has pulled back sharply in recent weeks.

Shares in the medical imaging software leader are down 13%, despite no change in the company's underlying fundamentals.

At Friday's close, Pro Medicus shares finished the session at $217.37.

For a stock that has delivered consistently over the long run, the recent weakness raises the question of whether the market has become too cautious.
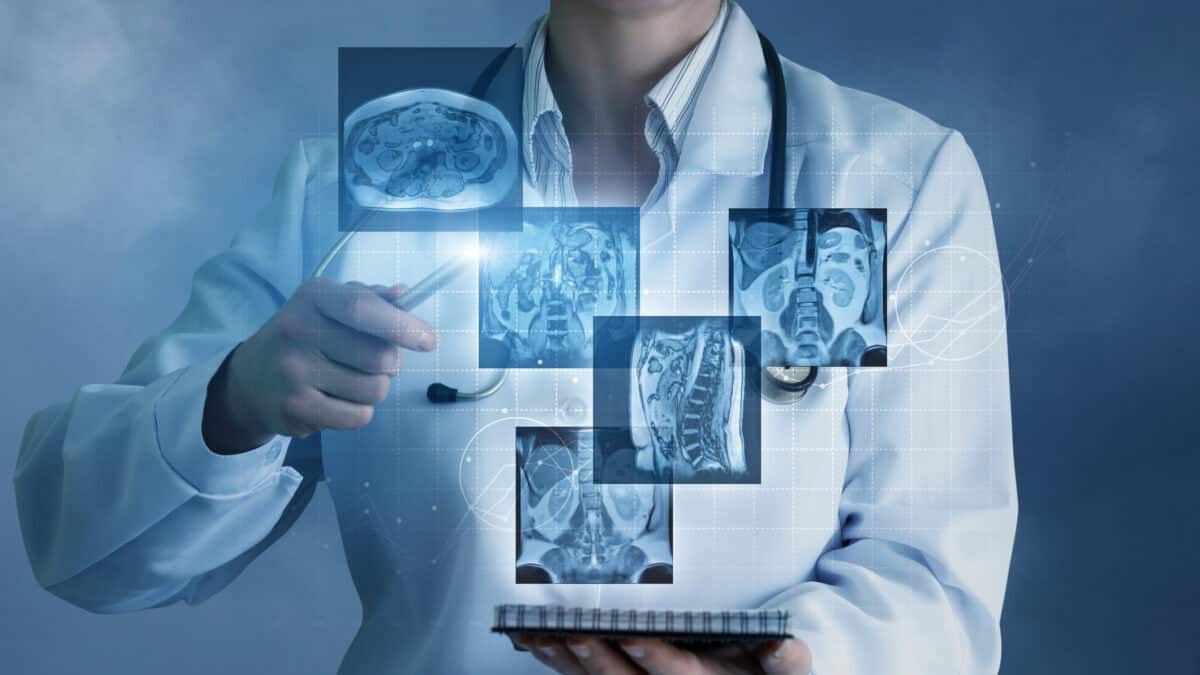
Doctor sees virtual images of the patient's x-rays on a blue background.

Image source: Getty Images

A rare pullback in a premium business

Pro Medicus has built a reputation as one of the highest-quality software companies on the ASX. Its Visage Imaging platform is deeply embedded in large hospital networks, particularly across the US, where long contract durations and high switching costs create a powerful moat.

The recent share price weakness appears more about valuation concerns and broader market volatility than company-specific issues. There have been no profit warnings, no loss of major customers, and no slowdown in contract momentum.

Contract wins continue to stack up

Just weeks ago, Pro Medicus announced another significant long-term contract with a large US healthcare group. The agreement covers a multi-year rollout across the customer's network, with room to expand over time.

That lines up with what management outlined at the latest AGM. Demand from US hospital systems remains strong, sales pipelines are deep, and existing customers continue to expand the platform's footprint.

Brokers remain firmly bullish

Despite the recent pullback, broker views on Pro Medicus haven't really changed.

Most major brokers continue to rate the stock as a buy, pointing to its long-term growth profile and ability to scale earnings as contracts roll through. Price targets remain comfortably above current levels, with many sitting in the $250 to $280 range.

Bell Potter has again highlighted Pro Medicus as a preferred healthcare name heading into 2026, citing its strong competitive position and clear revenue visibility. Similar themes are coming through across other broker updates, with analysts still seeing upside as new contracts ramp up and margins continue to expand.

Foolish takeaway

Rather than focusing on whether Pro Medicus is cheap, the real question is whether anything has changed. Right now, it's business as usual.

Contract momentum remains solid, broker confidence hasn't wavered, and management continues to point to a deep pipeline of US opportunities. In that context, the recent pullback looks more like a shift in sentiment than any change in the underlying story.

For investors watching the stock, this phase may be less about picking the exact bottom and more about gradually building exposure to a high-quality ASX 200 company.
Motley Fool contributor Aaron Teboneras has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has recommended Pro Medicus. The Motley Fool Australia has recommended Pro Medicus. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Blue Chip Shares

Couple on their laptop in their home kitchen.
Blue Chip Shares

Telstra vs NAB: Which ASX blue chip is the better buy?

I'm tipping Telstra over NAB for a better balance of income, franking, and recent share price momentum right now.

Read more »

Time to sell written on a clock.
Broker Notes

Sell alert! Why this expert is calling time on Woolworths and CBA shares

A leading expert believes investors would do well to exit their Woolworths and CBA share holdings. But why?

Read more »

Person holding a blue chip.
Blue Chip Shares

2 ASX blue-chip shares offering big dividend yields

These stocks could provide investors with pleasing passive income.

Read more »

Sad man sitting at desk and grabbing his head as he looks at a laptop.
Blue Chip Shares

Top 3 ASX shares I'd buy after the most recent sell-off

Three ideas while the market is nervous.

Read more »

Elder woman typing on her laptop.
Blue Chip Shares

2 ASX blue-chip shares offering big dividend yields

These stocks are providing investors with pleasing dividends…

Read more »

A young woman holds her hand to her ear and leans sideways as if to listen to something that's surprising her as her eyes and her mouth are wide open.
Blue Chip Shares

Buy, hold, sell: BHP, CSL, CBA shares

Brokers have given their latest verdicts on these ASX shares.

Read more »

Man using his device in an airport.
Blue Chip Shares

Top 3 ASX shares to buy with $3,000 in September

Income, leverage and defence in one parcel.

Read more »

A U.S. Naval Ship (DDG) enters Sydney harbour.
Blue Chip Shares

Austal shares are surging. Is a bidding war brewing?

Two suitors, one American shipyard.

Read more »