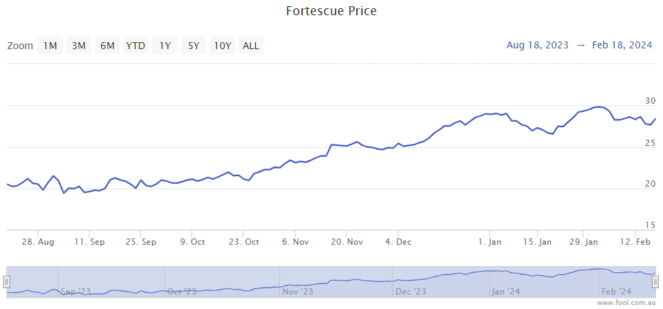
Fortescue Ltd (ASX: FMG) stock has achieved sizeable gains in the past few months. Could the ASX mining share be bigger than the Commonwealth Bank of Australia (ASX: CBA) by 2026?
Image source: Getty Images
How big is Fortescue now?
Fortescue's market capitalisation is now higher than Wesfarmers Ltd (ASX: WES), Macquarie Group Ltd (ASX: MQG), ANZ Group Holdings Ltd (ASX: ANZ) and Westpac Banking Corp (ASX: WBC).
ANZ currently has a market cap of around $85 billion, Westpac sits at $86 billion, and Fortescue has a market cap of $89 billion.
In the last six months, the Fortescue share price has lifted by 39%.
How big is CBA? It has a market capitalisation of $195 billion at the time of writing.
So, Fortescue would have to more than double in size to reach the level that Australia's biggest bank is currently at. It seems unlikely that Fortescue can rise that much in a relatively short time, and that doesn't even account for the possibility of CBA shares rising – though they could fall.
But, if Fortescue stock were to reach the market cap heights of CBA, there could be three things that power it there, in my opinion.
Stronger iron ore price
I think the biggest reason for Fortescue's recent rally is the strength of the iron ore price.
Six months ago, it was close to US$100 per tonne, and now it's up to US$130 per tonne. Iron ore costs roughly the same each month to mine, so any extra revenue for that production largely translates into extra net profit (aside from paying more to the government).
The current iron ore price has been achieved at a time when the Chinese property sector is reportedly weak. If the Chinese economy and the property sector can rebound, that could push the iron ore price higher, leading to stronger profitability for Fortescue.
It's impossible to know what the iron ore price is going to do. Forecasting it to go materially higher from here may be too optimistic.
More production
Another way to increase revenue would be to produce more iron ore. I'm not sure Fortescue can produce much more at its current projects that are already at full production.
But it's certainly possible that the high-grade Iron Bridge project could produce more as it ramps up.
Fortescue also has the high-grade Belinga iron ore project in Africa, which it believes "will one day be among the largest iron ore mines in the world". While it may take longer than 2026 to reach full production, the market may price in some of the potential improvements that Fortescue could experience.
Fortescue noted that the Belinga project opened "growth opportunities for Fortescue throughout Africa".
More production, combined with a good iron ore price, enables the miner to make good profits. I think it's vital the iron ore price stay high if Fortescue is to have any chance of overtaking CBA in the next few years. It obviously can't control what's happening with the iron ore price.
Green energy
One of the most exciting elements of Fortescue stock is the company's growth plans in green hydrogen, green ammonia and high-performance batteries.
It has a long-term goal of producing millions of tonnes of green hydrogen annually, which could unlock a large new earnings stream for the business.
In the long term, I think the energy division (and Fortescue Capital) could be what gets Fortescue shares the closest to CBA.
But it's also the riskiest – is Fortescue putting its money to good use? Will there be enough demand for this green energy? Will customers want to pay the amount that Fortescue needs to make a good profit on the money it has invested?
I wouldn't bet on Fortescue being a bigger business than CBA by the end of 2026, but investor excitement about Fortescue's energy division could help a lot as the main production gets closer.