I'm still seeing plenty of attractive long-term ASX share opportunities which are trading at cheap prices.
Low prices don't usually stay low forever if the market has become too pessimistic about a business.
Taking into account the potential long-term performance, I think the market has been overly negative on retailers and, generally, ASX small-cap shares. Below are three cheap ASX shares I think will be trading at much better prices in three years.
Image source: Getty Images
Adairs Ltd (ASX: ADH)
Adairs is an ASX retail share that has suffered a 70% fall since June 2021. It's understandable that the market is less optimistic about a furniture and homewares retailer than two years ago, but the sell-off seems overdone on a long-term view. As we can see on the chart below, the Adairs share price is close to its five-year low if we exclude the worst of the COVID-19 crash.

I think the businesses of Adairs, Mocka and Focus on Furniture have an attractive future.
The ASX share can add more (and larger) stores for Adairs and Focus on Furniture, it can sell Mocka furniture in stores, it can maximise the potential of its new national distribution centre, it can improve its cost base and benefit from Australia's growing population.
Based on the projections on Commsec, the Adairs share price is valued at 6 times FY25's estimated earnings with a possible grossed-up dividend yield of 15.4%. This could be a really cheap ASX share.
Close The Loop Ltd (ASX: CLG)
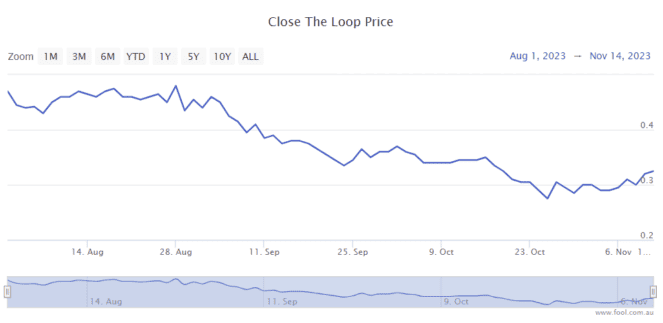
This is an ASX small-cap share that has dropped off around 33% since mid-August, as we can see on the chart below.
It has locations in Australia, Europe, South Africa and the US. The business creates "innovative products and packaging" that include recyclable and made-from-recycled content, as well as collecting, sorting, reclaiming and reusing resources that would otherwise go to landfill.
Examples include recovering a wide range of electronic products, print consumables, eyewear and cosmetics, and reusing toner and post-consumer soft plastics for an asphalt additive.
In other words, it's heavily involved in sustainability and the circular economy.
FY23 was a very strong year for the ASX share – revenue increased 52% to $135.9 million, gross profit rose 68% to $47.6 million and operating profit went up 81% to $22.4 million. I love seeing profit margins rise. It made underlying earnings before interest, tax, depreciation and amortisation (EBITDA) of $24.3 million, up 70%, which excludes the ASX listing fees.
In FY24 it's expecting revenue to grow to at least $200 million and EBITDA of at least $43 million, implying growth of at least 47% for revenue and 77% for EBITDA.
According to the projection on Commsec, the business is trading at less than 10 times FY25's estimated earnings. This seems like a very cheap ASX share to me, for how much growth it could make this decade.
Accent Group Ltd (ASX: AX1)
Accent Group is one of the largest shoe-selling businesses in Australia. It has some of its own brands, including The Athlete's Foot, Glue Store and Nude Lucy. The company also acts as the distributor of a wide number of shoe brands like Skechers, Timberland, CAT, Hoka, UGG, Hoka, Vans, Kappa and so on.
The Accent share price is down more than 20% from April 2023, as we can see on the chart below.
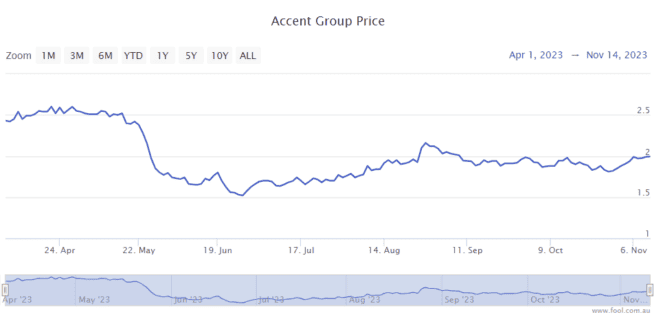
Accent has continued to grow its store network. It's expecting to open at least 50 new stores in FY24, achieve growth from existing and new distributed brands, as well as focusing on a "continued drive on cost efficiency and gross margin improvement." Total sales for the seven weeks of FY24 were up 2.8% compared to last year. – I think that's impressive, under the circumstances.
I think the strength of the brands, the store rollout and the impressive e-commerce presence can help the company.
According to projections on Commsec, the Accent share price is valued at 13 times FY25's estimated earnings with a possible grossed-up dividend yield of around 10%. It seems like a cheap ASX share to me.