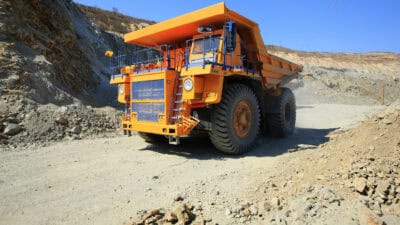
Sandfire Resources Ltd (ASX: SFR) is forging ahead at full operational capacity at its copper mine in Western Australia. The company recently announced that they continue to progress with mining, processing and sales in line with previously published guidance.
However, the company rightly hedged its guidance based on the massive level of coronavirus uncertainty we are all dealing with, making it clear that anything could happen at any time to change guidance.
At this strange point in our history, nobody's guidance is worth anything at all unfortunately.

The benefit of continuity
The fact that Sandfire has remained operational up until now is a big deal within the copper sector. In the past week, many copper mines and projects around the world have stopped or slowed. This includes mines up and down South America.
This includes the second largest global producer Codelco, which is preparing to slow production, a slowing of the $5 billion Quellaveco construction project in Peru, and the slowing of the Rio Tinto Limited (ASX: RIO) Oyu Tolgoi copper mine in Mongolia.
Demand has dropped off significantly. Last week the copper price per pound reached its lowest point since 2016, while at the same time copper inventories were at an all time high. However, this market is turning – late last week saw copper inventory levels drop by 0.7% and manufacturers in China reliant on the use of copper have commenced again in Wuhan, as well as across the rest of China.
Under these circumstances the closure of many copper mines for a limited period will see inventory levels drawn down significantly. Depending on the duration of the closures, it may also lead to sales opportunities for those companies that are able to maintain production.
The value of copper
The Sandfire share price has dropped by 47.12% since the start of the year and presently sells at a earnings multiple (P/E) of 5.55 (at the time of writing). Since it started earning revenue, the miner's average annual P/E has been 12.
It hasn't sold at this price since 2009. As an indicator of the company's value, it has an earnings yield of 21.5% while at the same time running with a return on capital employed of 23%.
Sandfire's DeGrussa mine is undoubtedly one of the premier high grade copper mines in the Asia region with a grade of 5%. Add to this the fact it produces gold as a byproduct with a grade of 2 g/tonne. This is a great source of additional revenue at a time when the gold price in Australian dollars is among the highest it has ever been.
Foolish takeaway
DeGrussa is operated very conservatively. As a copper mine, Sandfire has been able to maintain high margins throughout its operating life and is going to benefit greatly from the vacuum in supply due to coronavirus, as well as the lowest exchange rate for 18 years.