
The Wesfarmers share price has jumped 30% in a year, is it too late to buy?

It has been a strong period for Wesfarmers. Have investors missed their chance?

The Wesfarmers Ltd (ASX: WES) share price has done very well, rising by roughly 30% in the past year. Not many S&P/ASX 200 Index (ASX: XJO) shares have managed that level of strength.
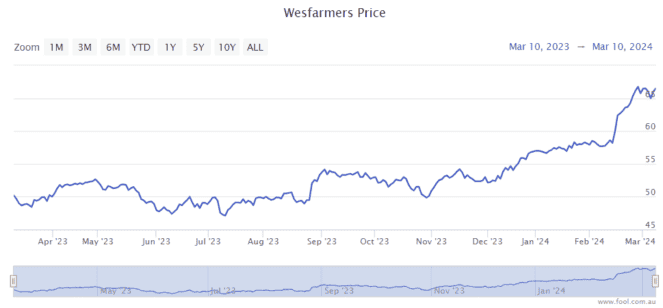
It's clear that the Wesfarmers share price is a lot higher. Now, without a crystal ball, I don't know if — or when — stock in the ASX retail conglomerate will ever fall back to its former levels.

And what happens next?

Is the Wesfarmers share price done rising? Or will it ride higher again?
A woman sits on sofa pondering a question.

Image source: Getty Images

Why I'm confident Wesfarmers' share price and profit can keep rising

In the long run, rising profit will typically boost a company's share price.

And there are a number of drivers that can help Wesfarmers keep growing profit.

For starters, the Australian population continues to grow each year, which increases the potential number of customers at stores like Bunnings, Kmart and Officeworks.

Next, the company has a healthy dividend payout ratio, which is the percentage of profit that is paid as a dividend.

In the FY24 first-half result, Wesfarmers reported a dividend payout ratio of 72%. That means it kept more than a quarter of its profit to re-invest in more growth initiatives – it would be appealing if it could continue achieving a return on equity (ROE) of more than 30% (it was 31.4% in HY24) on the additional profit that's re-invested.

Acquisitions can also boost the company's profit in the future. For example, it recently acquired Instantscripts and Silk Laser Australia to help boost the scale and diversity of its growing healthcare division.

Finally, I think Bunnings and Kmart are two of the best retailers in the country. In this high cost-of-living environment, I think they're both capable of winning market share, even if retail sales across Australia are challenged.

Valuation

According to the estimate on Commsec, the Wesfarmers share price is valued at 25x FY26's estimated earnings. I think that's a reasonable value for a long-term investment in this great business.


Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended Wesfarmers. The Motley Fool Australia has positions in and has recommended Wesfarmers. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Opinions

A man thinks very carefully about his money and investments.
How to invest

Cash rate at 4.6%: Here's how I'm investing in ASX shares

Interest rate hikes cut both ways.

Read more »

Man on a ladder drawing an increasing line on a chalk board, symbolising a rising share price.
Opinions

Is WiseTech the most undervalued growth stock on the ASX 200?

Has the sell-off gone too far?

Read more »

Signs of asset classes on a newspaper which says 'Where to invest your money?'.
Opinions

Where I'd invest in ASX shares after the recent RBA rate rise

These investments now look very good value to me.

Read more »

A female runner climbs a set of stairs, running with strength and pace.
Opinions

Can the Xero share price climb back to $100?

Could Xero shares finally be ready for a comeback?

Read more »

A man rests his chin in his hands, pondering what is the answer?
Opinions

This ASX dividend share is near a 52-week low. Would I buy?

Is this beaten-down ASX dividend share worth buying today?

Read more »

A panel of four judges hold up cards all showing the perfect score of ten out of ten
Dividend Investing

Is this the ASX's perfect dividend stock?

This stock offers what no others can...

Read more »

Person on a tablet with buy and sell options for a stock on the screen.
Opinions

Xero shares have crashed 64%. Here's why I'm buying

Xero shares have plunged, but I'm seeing a buying opportunity.

Read more »

Man holding Australian dollar notes, symbolising dividends.
Opinions

Why I think Soul Patts shares are even more attractive after the FY26 result

This business offers enormous positives.

Read more »






