



The Siteminder Ltd (ASX: SDR) share price has climbed 20% over the past six months. I think it's one ASX small-cap share to watch for the long term, and there are good reasons why 2024 could be an exciting year.
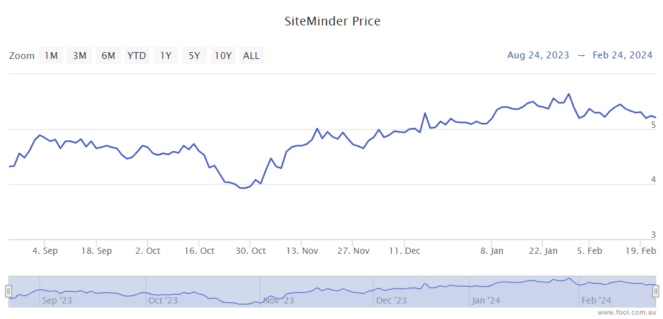
Siteminder describes its software as "the only platform that unlocks the full revenue potential of hotels" and an "all-in-one hotel management software that makes the lives of small accommodation providers easier".
It has offices in Bangalore, Bangkok, Barcelona, Berlin, Dallas, Galway, London and Manila and generates more than 115 million reservations worth over $70 billion in revenue for its hotel customers annually, according to the company.
Image source: Getty Images
Strong growth
The company is seeing growth in a number of different metrics, which are all contributing to its overall growth. Proof of its success is coming out with the numbers.
It recently reported its FY24 first-half numbers which showed total revenue growth of 27.9% to $91.7 million, with subscription revenue rising 23.8% to $60.3 million and transaction revenue jumped 36.5% to $31.4 million.
Annualised recurring revenue (ARR) rose 27.2% to $182.5 million in the half-year update.
Siteminder advised the number of customer properties increased 13.7% to 41,600. More hotels boost the number of potential transactions that can occur.
But it will take a full 12 months for the business to display its 12-month revenue potential, so the next year already has more growth baked in for the ASX small-cap share.
The ASX small-cap share's profitability is rapidly improving
Siteminder is still making negative cash flow, but the ratio to sales is rapidly improving and looks very promising. In the second quarter of FY24, it saw negative underlying free cash flow of 7% of revenue (being negative $3.1 million), which was an improvement from 28.4% in the same period last year.
The company expects to be profitable in the second half of FY24 for both underlying earnings before interest, tax, depreciation and amortisation (EBITDA) and underlying free cash flow.
Siteminder pointed out that its growing margins reflected the scalability of the business and disciplined cost management.
The company's rapidly growing revenue should help its profit margins in the coming years.
I think reaching breakeven could be a strong catalyst for the company.
Strong outlook
The business is steadily investing in creating new offerings for subscribers, which can help increase loyalty, deliver more growth for subscribers and create revenue for itself.
It's targeting organic revenue growth of 30% in the medium term. Any business compounding at that rate for a number of years will naturally grow into a bigger company.
With an annual recurring revenue (ARR) of $182.5 million already, it appears to have a good growth outlook for at least the next 12 months.
While I wouldn't call the ASX small-cap share cheap, I think it has lots of growth potential with its own financials and for shareholders.








