If an ASX biotech stock has almost tripled in 6 months but the valuation still remains "cheap", then you would be careless to not at least consider adding it to your portfolio.
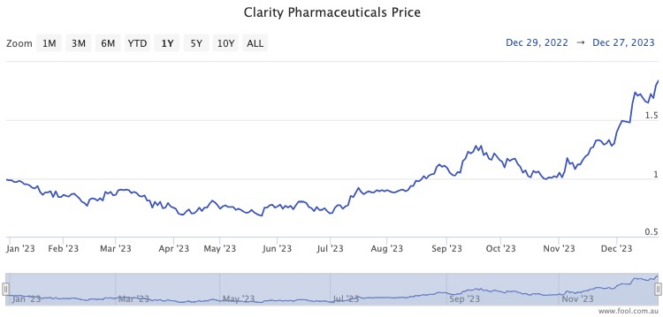
According to Frazis Capital portfolio manager Michael Frazis, Sydney company Clarity Pharmaceuticals Ltd (ASX: CU6) has been "on a bit of a tear".
"This is the most exciting company I've come across in Australia lately," he said in a memo to clients.
"Clarity has been steadily releasing data from patients treated with their copper therapies with late stage prostate cancer."
That data has apparently been favourable, causing the share price to rocket 179% from its 52-week low in late June.
Image source: Getty Images
Biotechs snapped up for billions with early data
Frazis said that mergers and acquisitions activity in the global biotechnology industry has been "intense".
And those transactions provide some clues as to how undervalued Clarity Pharmaceuticals still is, despite the spectacular rise the last few months.
"If their data continues to hold, this is still early days, and it remains a fraction of the value of recent acquisitions in the space with early stage data."
Just last week US$100 billion giant Bristol-Myers Squibb Co (NYSE: BMY) acquired RayzeBio Inc (NASDAQ: RYZB) for US$4.1 billion, on the back of early data for its gastroenteropancreatic neuroendocrine tumour therapy and the start of a phase III trial.
"And Novartis AG (SWX: NOVN) paid US$2 billion for Endocyte in late 2018 with only Phase II data," said Frazis.
"This has proved a big winner, with first year revenues for their first product Pluvicto forecast at over US$1 billion."
This week Eli Lilly And Co (NYSE: LLY) completed its acquisition of Point Biopharma Global Inc (NASDAQ: PNT) for US$1.4 billion with only phase II data.
This is why Frazis believes that the Clarity share price remains a bargain despite the massive appreciation this year.
"In a space where companies with promising data are being acquired for billions of dollars, and Clarity's early indications look best-in-class, the company's post-runup US$340 million valuation looks cheap."
'Double or even triple industry revenues'
Prostate cancer will be "a large market", according to Frazis.
"The trend is towards increased monitoring and — where possible — fewer surgeries and hormone therapy, which involves the unwelcome side effects of incontinence, impotence, low testosterone and depression."
Currently the biotechs are treating "heavily pretreated patients", but in the longer run their solutions could be applied more proactively.
"The hope is that these targeted treatments, with their milder side effects, will move further up the treatment timeline, which could double or even triple industry revenues," said Frazis.
"This will take time, given the high hurdle for changing standard-of-care, but is looking more likely than ever today."
In the short term, both incidence and diagnosis is increasing for prostate cancer, which will keep feeding Clarity's valuation.
While the biotech stock is sparsely covered, at least Jefferies and Wilsons analysts agree with Frazis. Both teams rate Clarity Pharmaceuticals as a strong buy, as shown in CMC Invest.