Why I think the Corporate Travel share price is a strong buy right now

I believe this stock can keep flying higher.

| More on:

You’re reading a free article with opinions that may differ from The Motley Fool’s Premium Investing Services. Become a Motley Fool member today to get instant access to our top analyst recommendations, in-depth research, investing resources, and more. Learn More

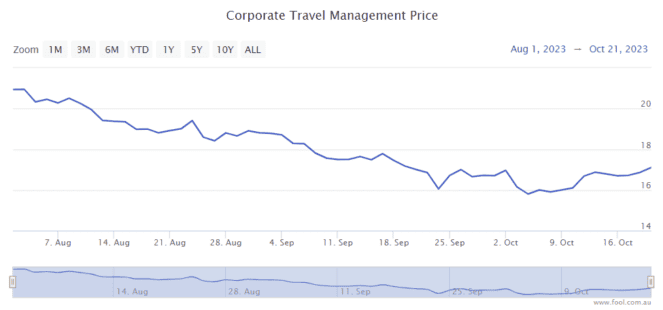
The Corporate Travel Management Ltd (ASX: CTD) share price has dropped 20% since the start of August, as we can see in the chart below. The ASX travel share's ongoing progress makes me think this pullback is an investment opportunity.
This company provides travel services to businesses, and has become one of the five largest travel management companies in the world.
Man sitting in a plane looking through a window and working on a laptop.

Image source: Getty Images

Strong growth

Corporate Travel's latest update for the first three months of FY24 is very promising. It showed 36% revenue and other income growth to $187.9 million, with underlying earnings before interest, tax, depreciation and amortisation (EBITDA) growth of 157.3% to $56.6 million.

The fact that the EBITDA margin improved from 15.9% to 30.1% is pleasing to see. It shows the business is very scalable as revenue recovers to pre-COVID levels (and beyond).

Its large client activity in North America, Australia, New Zealand and the EU is "gradually improving", with this segment being described as a "recovery laggard". That implies there's more room for short-term recovery growth in this segment.

Another positive for Corporate Travel Management shares is its new client wins of $0.35 billion, including verbal wins, in the first quarter of FY24.

The company also revealed that automation and AI projects were "well underway" and expected to have a "positive productivity impact" for many years.

The company also noted that the global travel market was estimated to grow at 7.9% per annum between FY23 to FY26, which is a useful tailwind for earnings.

Management is targeting a "mid-teen double-digit" compound annual growth rate (CAGR) in earnings per share (EPS) terms beyond FY25. FY24 is expected to be a record EPS year, according to the ASX travel share.

Better valuation

When a business is growing profit, a fall in its share price results in a more attractive price/earnings (P/E) ratio.

According to the projection on Commsec, Corporate Travel is forecast to generate $1.05 of EPS in FY24. If it delivers on that prediction, it would mean a forward P/E ratio of less than 16. This seems very reasonable to me, considering there could be more good growth in FY25 and beyond.

It could pay an annual dividend per share of 50 cents, which would translate into a dividend yield of 3% — a useful bonus.

Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has positions in and has recommended Corporate Travel Management. The Motley Fool Australia has recommended Corporate Travel Management. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Opinions

A rocket blasts off into space with planet behind it.
Opinions

SpaceX shares are flying. Here's the price I'd wait for

SpaceX is on my watchlist, but I’m staying patient.

Read more »

Drone flying in the sky.
Opinions

DroneShield shares have crashed 51% in a year. Here's why I'd buy them today

DroneShield has plenty of risks, but its the that upside interests me.

Read more »

A male oil and gas mechanic wearing a white hardhat walks along a steel platform above a series of gas pipes in a gas plant.
Opinions

Santos shares are up 40% in 2026. Here's why I'd still buy them today

A big rally hasn’t changed my view on this ASX energy stock.

Read more »

A container ship passes beneath a suspension bridge.
Opinions

WiseTech shares have been smashed in 2026. Here's why I wouldn't bet against them

Investors have turned bearish on WiseTech, but I wouldn’t write it off yet.

Read more »

Engineer in the oilfield wearing red helmet and work clothes, with pumpjack and wellhead in the background.
Energy Shares

Why I'd buy Santos and Woodside shares today

Santos and Woodside shares are up more than 40% in 2026 and paid two dividends. Here's why they could have…

Read more »

Drone flying in the sky.
Opinions

DroneShield shares are down 75%. Could this huge short bet backfire?

Could this heavily shorted ASX stock be ready to bounce?

Read more »

A construction worker sits pensively at his desk with his arm propping up his chin as he looks at his laptop computer.
Gold

Down 16%, could this $2 billion activist bet wake up Northern Star shares?

A major activist investor is turning up the pressure.

Read more »

Happy work colleagues give each other a fist pump.
Opinions

Megaport shares have surged 10% in a week to $18. I think they could hit $25

This tech stock could have plenty more upside from here.

Read more »