With a P/E ratio of 15, is this ASX All Ords share price too low to ignore?

I think this stock still has more to go.

The All Ordinaries Index (ASX: XAO) share GQG Partners Inc (ASX: GQG) has risen strongly. Does it have a low enough price/earnings (P/E) ratio to buy?
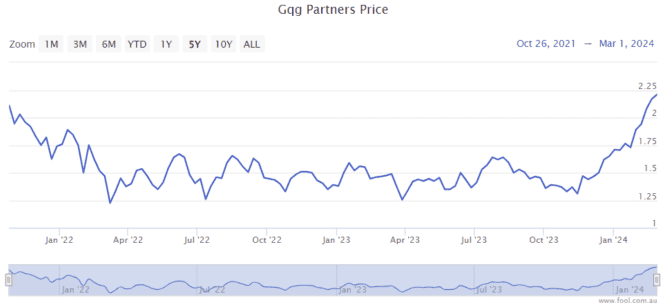
GQG shares have risen 50% in the past six months, soundly outperforming the 6% increase for the S&P/ASX 200 Index (ASX: XJO).

The fund manager was very undervalued before, and I still think the ASX All Ords share is undervalued now, following continued growth.
A male investor sits at his desk looking at his laptop screen holding his hand to his chin pondering whether to buy Macquarie shares

Image source: Getty Images

Why 2024 looks like another good year for the All Ords ASX share

The funds management space is difficult for the industry as a whole. Low-cost exchange-traded funds (ETFs) are capturing a lot of investment inflows.

However, not all fund managers are suffering, GQG is one of the rare ones doing very well.

In the 2023 full-year result it reported net flows of US$10 billion, a 14.7% increase of the average funds under management (FUM) to US$101.9 billion, a 17.4% rise in distributable earnings to US$297.9 million and a 17.3% rise in the dividend per share to US 9.1 cents per share.

Those numbers are impressive, but they tell us about the past. What about the future?

The average FUM for 2023 was US$101.9 billion and closing FUM at December 2023 was US$120.6 billion. That implies an 18% increase of FUM, if the FUM weren't to change. But, it has changed – FUM at January 2024 was US$127 billion (with net inflows of US$1.9 billion), 24.6% more than 2023's average FUM.

Unless there's a sustained crash of the global stock market, it seems GQG is on track to report an increase in earnings (and the dividend) of more than 20%.

Fund managers are typically scalable businesses – if FUM rises by 10%, it doesn't require 10% more employees or 10% more office space to manage that increased capital. Profit margins can rise as FUM grows.

Cheap valuation

If we assume a 20% rise in EPS for the ASX All Ords share in 2024, it would put the GQG share price at under 13 times FY24's possible earnings with a potential dividend yield of 7.6%.

I'm not going to assume that GQG's FUM can grow forever, but for the next year ahead it still looks undervalued with how well its investment funds are performing and how much it's bringing in with net inflows.

If the ASX All Ords share can keep increasing its geographical footprint and winning new clients, it may have an extended growth runway that the market isn't appreciating. The attractive flow of dividends is helping boost returns.
Motley Fool contributor Tristan Harrison has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Opinions

A young woman sits with her hand to her chin staring off to the side thinking about her investments.
Opinions

CSL shares: I weighed up the bull and bear case, and here's my final verdict

The ASX biotech company has rebounded strongly from a multi-year low in June.

Read more »

A young woman sitting in a classroom smiles as she ponders lessons learned.
Opinions

I looked at the bear case for these 3 ASX shares, and came to a different conclusion. Here's why

Here’s my take on these three ASX shares.

Read more »

Broom sweeping cash into dust pan.
Opinions

Up 20%: Has the EQT deal saved Cleanaway shares?

Cleanaway's 20% jump takes it back to 2022 prices.

Read more »

Person holding Australian dollar notes, symbolising dividends.
Dividend Investing

75% of my dividends come from these 4 ASX shares (and I want to buy more)

I rate these stocks as top options for dividend income.

Read more »

One large yellow sphere on one side of a white seesaw, with a small yellow sphere on the other side.
Opinions

I investigated 3 ASX shares that have fallen sharply. Are they bargains or value traps?

I've given my verdict on three depressed high-profile stocks.

Read more »

Person pointing at an increasing blue graph which represents a rising share price.
Opinions

These are the best 3 ASX growth shares I own and I'd buy more of today

I’m bullish about the earnings potential of these three ASX growth shares.

Read more »

A woman holds an old fashioned telephone ear piece to her ear while looking unhappy sitting at a desk with her glasses crooked on her nose and a deflated expression on her face.
Communication Shares

Why have Telstra shares lost 16% since May?

Telstra has been a loser in recent months.

Read more »

A man and woman sit next to each other looking at each other and feeling excited and surprised after reading good news about their shares on a laptop.
Opinions

Buy, hold, sell: BHP, Westpac, and Zip shares

I weigh up the outlook for three popular shares to see which ones I would buy today.

Read more »