Whitehaven Coal share price charges higher on record half

Sky high coal prices have been good news for this miner…

Key points
  • Whitehaven Coal has released its quarterly update
  • The miner is benefiting greatly from sky high coal prices
  • This has led to its operating earnings more than quadrupling during the first half

The Whitehaven Coal Ltd (ASX: WHC) share price is on the move on Friday.

At the time of writing, the coal miner's shares are up 5% to $9.38.

This follows the release of the company's quarterly update, which revealed another three months of strong cash generation.
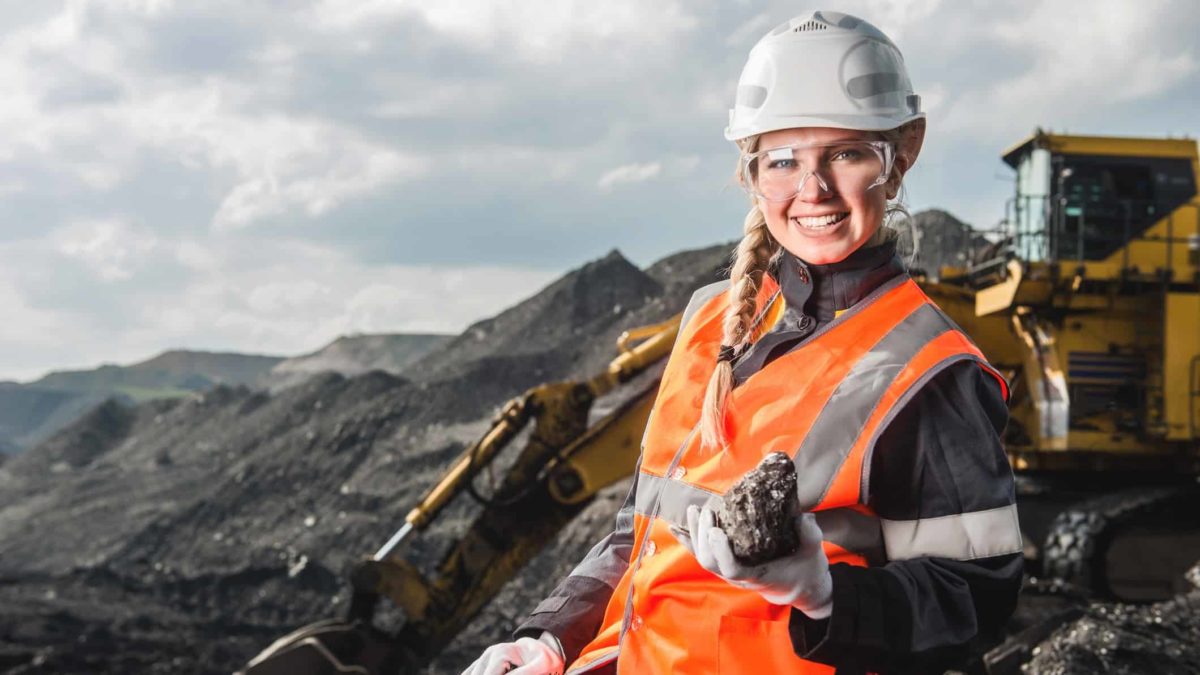
A female coal miner wearing a white hardhat and orange high-vis vest holds a lump of coal and smiles.

Image source: Getty Images

Whitehaven share price charges higher on record half

For the three months ended 31 December, Whitehaven Coal delivered managed run-of-mine (ROM) production of 4.8Mt, up 21% on the previous quarter and 50% on prior corresponding period.

This underpinned managed sales of produced coal of 4.3Mt, up 16% on the September quarter and 21% on the prior corresponding period.

And while prices softened a touch to an average of A$527 per tonne for the quarter, down from A$581 per tonne in the previous quarter, this was still more than double what it was commanding a year earlier. As a result, the company delivered a record average first half coal price of A$552 per tonne.

And with total managed sales coming in at 8Mt for the half, management revealed that the company expects to post record half year EBITDA of $2.6 billion. This will be more than quadruple the $0.6 billion reported in the prior corresponding period.

Combined with its strong cash generation, the company finished the half with a net cash position of $2.5 billion.

Management commentary

Whitehaven Coal's CEO, Paul Flynn, was pleased with the company's performance given the wet weather. He said:

During the December quarter, we maintained strong operational performance at our Narrabri underground mine which helped offset the impact of continued wet weather on volumes from our open cut mines.

Strong ongoing demand for high CV coal, coupled with supply constraints, underpinned high prices, a solid December quarter and an exceptional first half result. We generated $2.5 billion of cash from operations in the half year, including $1.0 billion in the December quarter. At the end of December, we held a net cash position of $2.5 billion.

The Company is performing well and delivering strong returns for our shareholders including buying back $593 million of shares in the first half of FY23. Energy security remains a key imperative for our customers throughout Asia, and we are continuing to supply high quality coal through the energy transition for the benefit of all stakeholders.

Outlook

No change has been made to the company's full year guidance.

Management advised that it remains on track to deliver within the range of its overall production, sales, and cost guidance for FY 2023.

This includes managed ROM coal production of 19 to 20.4Mt, managed coal sales of 16.5Mt to 18Mt, and unit costs of $95 to $102 per tonne.

Motley Fool contributor James Mickleboro has no position in any of the stocks mentioned. The Motley Fool Australia's parent company Motley Fool Holdings Inc. has no position in any of the stocks mentioned. The Motley Fool Australia has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy. This article contains general investment advice only (under AFSL 400691). Authorised by Scott Phillips.

More on Energy Shares

Engineer in the oilfield wearing red helmet and work clothes, with pumpjack and wellhead in the background.
Energy Shares

How many Woodside shares do I need to buy for $12,000 of passive income in 2027?

Woodside is a strong contender for dividends next year.

Read more »

Man holding a calculator with Australian dollar notes, symbolising dividends.
Energy Shares

If I invest $15,000 in Woodside shares, how much passive income will I receive in 2027?

Woodside could be a source of large passive income in 2027.

Read more »

Oil worker using a smartphone in front of an oil rig.
Energy Shares

How many Woodside shares do I need to buy for $1,000 per month of passive income?

Find out what you could earn off your oil and gas investment.

Read more »

Engineer in the oilfield wearing red helmet and work clothes, with pumpjack and wellhead in the background.
Energy Shares

Woodside Energy vs Ampol: Which ASX oil stock looks better this week?

Woodside Energy and Ampol both offer franked income, but one oil stock looks better value to me right now.

Read more »

An oil worker in front of a pumpjack using a tablet.
Broker Notes

2 ASX energy companies Macquarie says will outperform

There's still some value in the volatile energy sector, the broker says.

Read more »

Engineer at an underground mine and talking to a miner.
Broker Notes

Up 42% and paying a 7% dividend yield, should I buy New Hope shares today?

A leading expert delivers his outlook for New Hope’s outperforming shares.

Read more »

A man scratches his head in confusion.
Energy Shares

This ASX energy stock just crashed 12%. Here's what's gone wrong

Investors are heading for the exits.

Read more »

A woman wearing a black and white striped t-shirt looks to the sky with her hand to her chin, contemplating buying ASX shares.
Energy Shares

Boss Energy vs Paladin Energy: Which ASX uranium stock wins?

Boss Energy and Paladin Energy are ASX uranium leaders. Here’s which I’d buy based on value, growth, and latest performance.

Read more »