ASX 200 mining share Alumina Limited (ASX: AWC) is having a shocker this year.
The company has lost 36% of its value in the year to date.
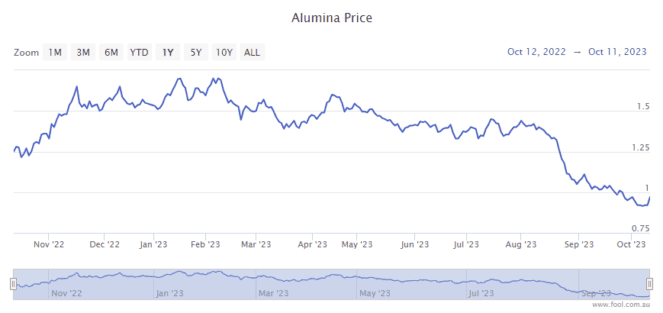
Last month, Alumina shares fell below $1 for the first time in 10 years.
On top of that, dividends have been suspended for the past 12 months. Prior to this, Alumina was an ASX 200 dividend darling with a five-year average yield of 7.4% fully franked.
Alumina is a holding company that owns a 40% stake in the world's largest alumina and bauxite producer, Alcoa World Alumina and Chemicals (AWAC), which is a division of Alcoa Corp (NYSE: AA).
Yesterday, Alumina shares closed at 97 cents, up 1.04%.
Last Thursday, the ASX 200 mining share hit a decade-low price of 90 cents.
So, is this a good time to buy? Let's investigate.
Image source: Getty Images
Why is this ASX 200 mining share floundering in 2023?
Contrarian fund manager Allan Gray owns almost $127 million dollars worth of Alumina shares.
This is the fourth largest position in Allan Gray's Australia Equity Fund Class A and B portfolio, at 6%.
Allan Gray managing director and chief investment officer Simon Mawhinney laments the ASX 200 mining share's performance this year in the September quarterly update.
He concedes that Alumina was the fund's "biggest detractor" during the quarter.
Mawhinney noted AWAC's soaring costs of production at both its Spanish and Western Australia operations.
Rapidly rising European gas prices led to production cuts at the San Ciprian refinery, with costs soaring to a peak of US$664 per tonne. They've since fallen to US$457 per tonne, but that's still well above the alumina price.
In Western Australia, regulatory delays are the problem. The WA Government has not renewed AWAC's rolling five-year mining management plan (MMP) for the Huntly bauxite mine. This follows a request in February from the WA Forest Alliance Group for a new environmental impact assessment. Allan Gray says the assessment will likely go ahead — and take years — with restrictions placed on production while it happens.
On top of that are considerably higher prices for other inputs like caustic soda. This has not been offset by alumina price rises and thus has led to losses for many producers, not just AWAC and Alumina.
All of this has pushed AWAC's cash costs from the low US$200s per tonne to well over US$300 per tonne today, says the fund manager.
The Alumina price is currently US$338.40 per tonne. You can see the problem, right?
A capital raise is 'near-certain' for Alumina
In September, Alumina revealed a net loss after tax of US$43 million for the first half of 2023. That was a dramatic decline from the US$168 million net profit after tax (NPAT) reported for 1H FY22.
Mawhinney comments that a "near-certain" capital raise is ahead for Alumina investors:
Adding salt to Alumina Limited's wounds, is its requirement to fund its share of AWAC's operating losses (predominantly from San Ciprian and Kwinana) or risk dilution of its 40% equity share in the joint venture. To do this, it has already accumulated US$221m of debt and has a facility limit of US$500m.
ASX 200 mining share 'significantly oversold'
Having said all that, Mawhinney thinks the ASX 200 mining share may have been "significantly oversold".
He commented:
We believe there are reasonable prospects for Alumina Limited to make US$400m in pre-tax earnings. The company trades for US$550/t of annual production (and even lower if you adjust for shut-in capacity), less than half the cost of newer higher-cost capacity in developing markets.
Even if Kwinana and San Ciprian were both closed and closure costs amounted to US$500m, Alumina Limited would still trade at a significant discount to the cheapest replacement capacity available.
The fundie points out that if Alumina did close both operations, this would remove a big chunk of global alumina production and likely push the commodity's price higher, as seen before in other situations.
In early-2018, Norsk Hydro's Alunorte refinery in Brazil was forced to run at 50% of its 6mtpa capacity due to environmental concerns … The impact on alumina supply was similar to a combined San Ciprian and Kwinana closure. By mid-April that year, alumina prices had rallied to US$710/t …
This is not to say that today's impact would be the same … our point is that it's unwise to make investment decisions in a vacuum. There are always second-order impacts of assumption changes, and, in Alumina's case, these might significantly increase the intrinsic value of its remaining production.
Sentiment on Alumina shares 'at an all-time low'
Allan Gray reiterates that it is "not unusual for the share market to overreact to uncertainty".
We can't say for certain what will happen to Alumina, but we do know that it's easy for investors to be constrained by short-term thinking and to anchor their thinking in the present.
If we can find an above-average company, at a weak point in its cycle when sentiment is low, we can increase your chances of upside. We believe sentiment for Alumina is currently at an all-time low.
Should you buy this ASX 200 mining stock?
On Wednesday, top broker Goldman Sachs raised its rating on Alumina shares from sell to neutral.
The broker said the upgrade was partly based on valuation grounds following the ASX 200 mining share's price decline.
It pointed out that Alumina shares were trading at approximately 0.65x the net asset value (NAV).
Goldman estimates the NAV as equivalent to $1.42 per share. That's pricing in a long-run alumina price of US$300 per tonne, which is less than Goldman's own long-run price assumption of US$330 per tonne.
The broker placed a 12-month share price target of $1.10 on Alumina. This implies a potential upside of 12% for investors who buy the dip today.
The consensus recommendation among brokers covering Alumina on CommSec is hold. Among eight analysts, two rate it a strong buy, two say hold, two say it's a moderate sell, and two say it's a strong sell.
The future: What do electric vehicles have to do with it?
Looking ahead, the rising popularity of electric vehicles (EVs) is a tailwind for global alumina demand.
Every EV has an average aluminium content of 250 kilograms. As EV manufacturers ramp up production, demand for aluminium will inevitably grow.
To clarify, alumina is a base input in aluminium production (and has other industrial applications, too).
In its latest quarterly report and outlook, the Australian federal resources department said:
A significant driver of aluminium demand is expected to come from world automakers seeking to reduce vehicle weight by increasing the proportion of aluminium in the vehicle.
Aluminium is 10-40% lighter than steel in comparable components. EV makers are particularly focused on reducing vehicle weight, since it impacts heavily on the driving range of the vehicle.
It is estimated that EV sales will rise from 8.2 million units in 2023 to 12.8 million units in 2025 in China.
In Europe, sales will rise from 3.8 million units in 2023 to 5.2 million units in 2025. And in the US, sales will go from 1.9 units in 2023 to 3.6 million units in 2025, according to the report.
This also means that the forecast demand for aluminium will rise from 2.1 Mt in 2023 to 3.2 Mt in 2025 in China, from 0.9 Mt in 2023 to 1.3 Mt in 2025 in Europe, and from 0.5 Mt in 2023 to 0.9 Mt in 2025 in the US.