The share price plunge comes after the defence tech company released its 3Q FY26 update after the close yesterday.
Today's fall is no doubt worrying for investors, given Elsight shares have plummeted 75% from a record $8.56 in May.
Let's take a look at the 3Q numbers.
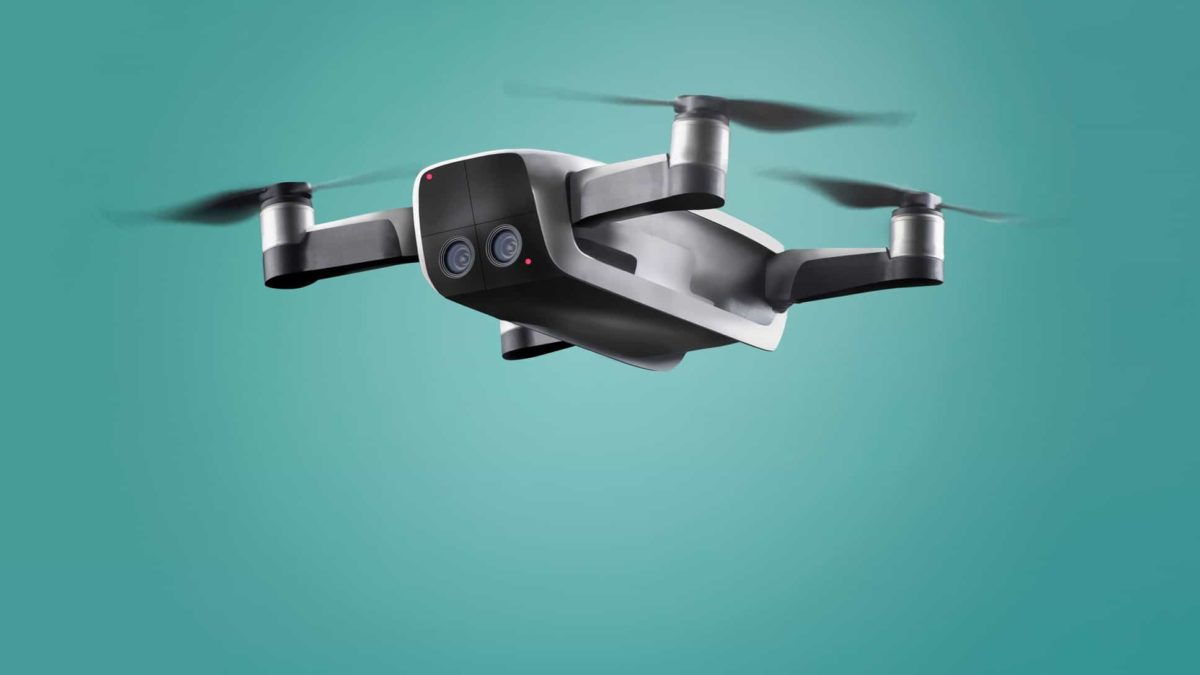
Image source: Getty Images
Elsight shares plunge on weaker third quarter
Elsight develops technology that enables unmanned surveillance and military operations.
Elsight's products serve defence, public safety, and commercial markets across air, land, and maritime applications.
Its flagship product, Halo, provides Beyond the Visual Line of Sight (BVLOS) connectivity for drones, UAVs, and other unmanned systems.
Halo was launched in 2020, and today, more than 100 drone and UAV manufacturers and operators are using it for connectivity.
Elsight reported results that were below management's expectations for 3Q FY26.
Unaudited revenue came in at approximately US$2.4 million. There was a non-GAAP loss of approximately US$700,000.
However, the company pointed out that its revenue over the first three quarters of FY26 was 91% higher at US$25.8 million.
Elsight said:
Management views the quarter as a temporary fluctuation in a business where results can vary from quarter to quarter.
Elsight said it has a pipeline of new work worth US$196 million, up from $168 million at the end of 2Q FY26.
The company said:
The current pipeline reflects opportunities identified to date and should not be interpreted as a revenue forecast for 2027.
We expect further growth as additional opportunities develop and new products planned for launch in the coming months and contributing to revenue.
These products are not yet included in the pipeline and are expected to make a significant contribution over time.
Elsight was holding US$59.4 million in cash and cash equivalents, with no debt, as of 30 September.
During 3Q, Elsight said it had expanded its US Army procurement access and its manufacturing capacity in the US and Germany.
Last month, Elsight signed a Basic Ordering Agreement with the US Army and secured an early listing on its UAS Marketplace.
Should you buy the dip?
In a new note issued today, top broker Bell Potter maintained its buy rating on the S&P/ASX 200 Index (ASX: XJO) tech share.
This was despite the company substantially missing the broker's expectations of US$6 million in revenue for 3Q FY26.
The broker cut its 12-month share price target from $8.20 to $5.30.
This still implies substantial share price growth of 150% over the next year.
Analyst Baxter Kirk explained their point of view:
Order delays have led to a disappointing 3Q26 for ELS.
Nevertheless, we believe the market has underappreciated the AV Mayhem10 product integration which acts as a key validator for the Halo offering and helps reduce customer concentration risk in CY27.
Catalysts: OEM1 repeat order and non-OEM1 orders over next 3 months; passing of the US FY27 US defence budget spurring downstream customer orders.
Elsight share price snapshot
Elsight shares are down 38% in 2026 vs. a 2% rise for the benchmark ASX 200.
The tech company was one of the standout success stories of FY26 for share price growth.
The Elsight share price soared 300% over the 12 months to 30 June.
That led to Elsight ascending into the ASX 200 in the September quarter rebalance.